Dear visitor
You tried to access but this page is only available for
Witold Bahrke
Senior Macro and Allocation Strategist
EM Debt when the cycle matures
Relative resilience
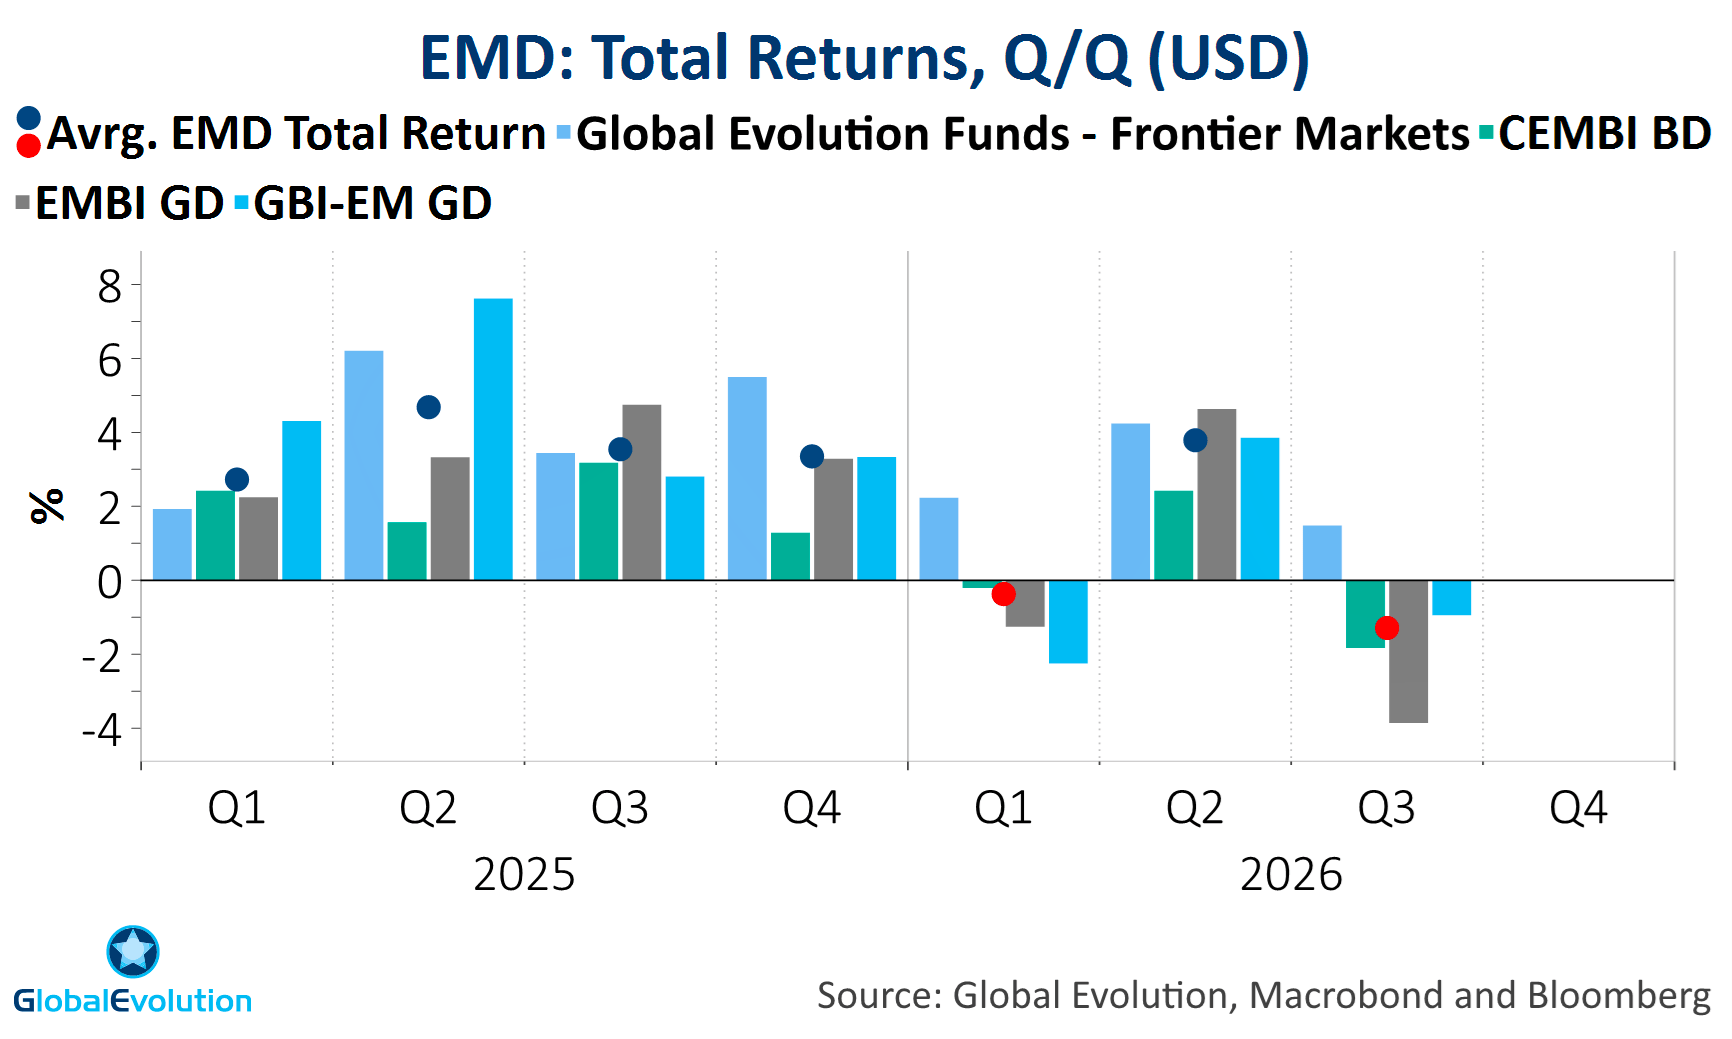
EMD has weathered the (rates) storm relatively well: Q3 drawdowns much smaller than in core fixed income. Similar returns to US HY, which has much lower duration, though.
Rollercoaster
YTD, EMD returns showed typical late-cycle volatility as monetary conditions tightened.
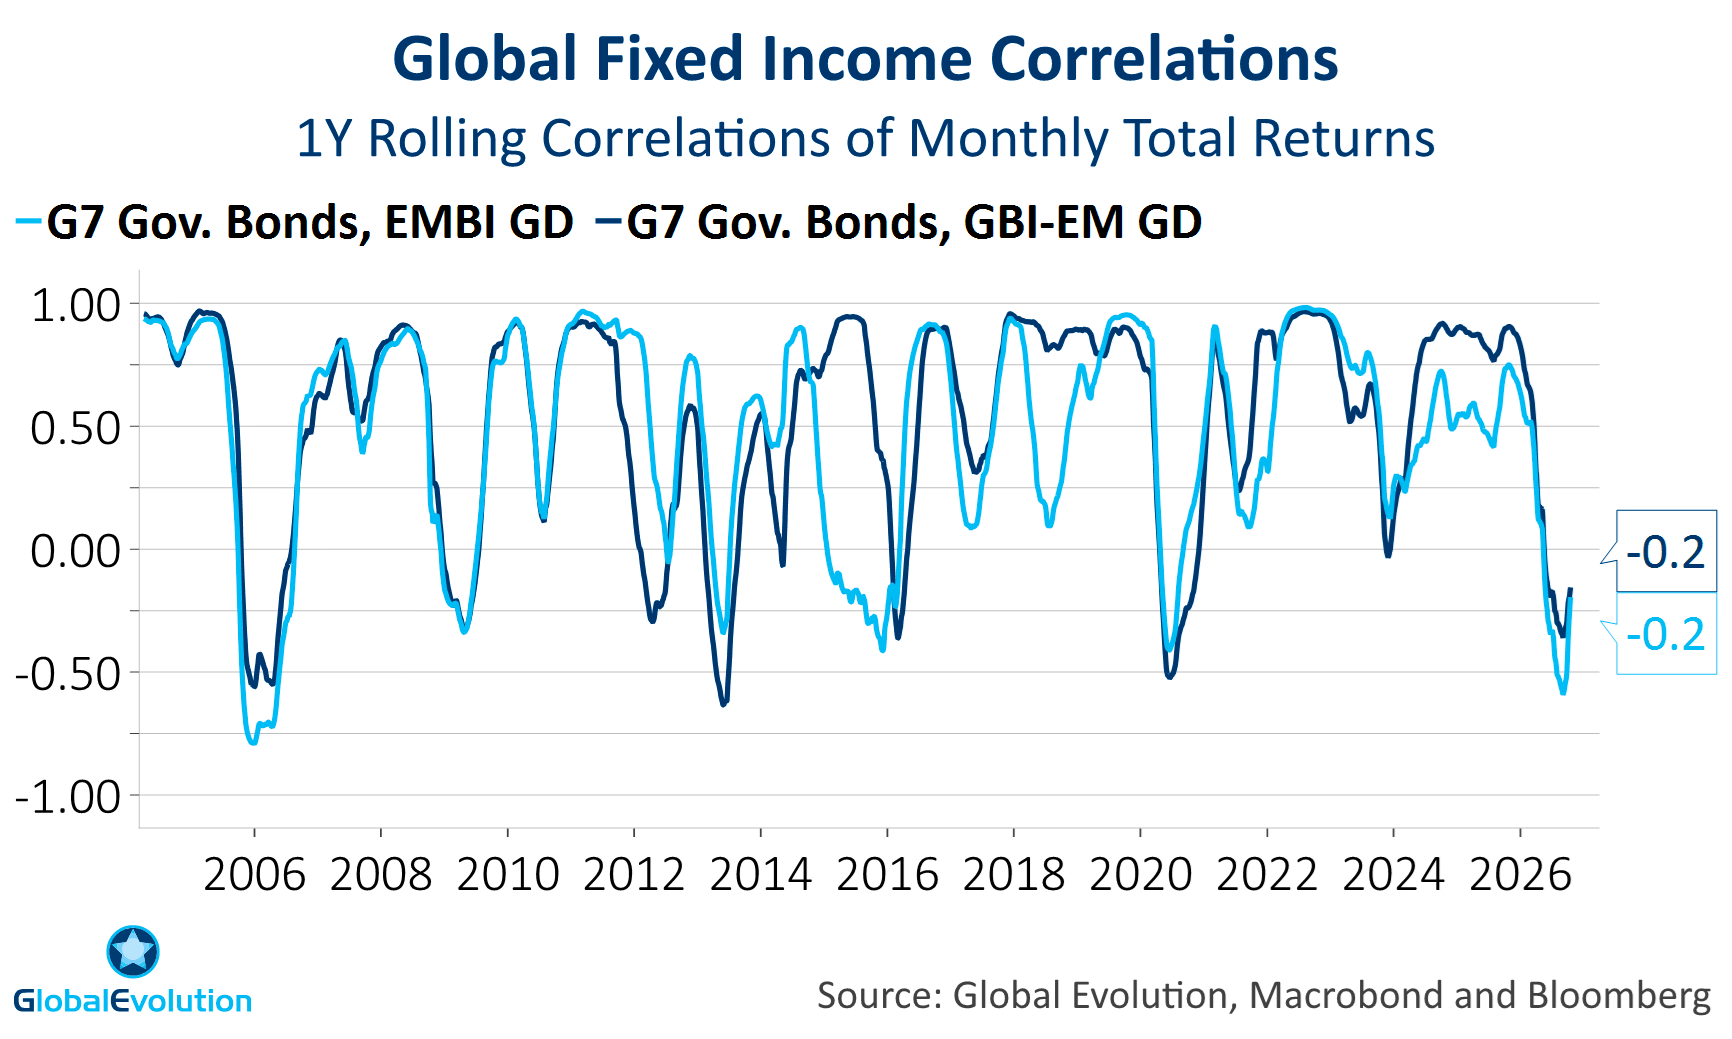
EMD as diversifier
Correlations with G7 bond returns are negative over the past 12M.
MACRO: K-shaped economy keeps monetary tightening risks in check
Growth
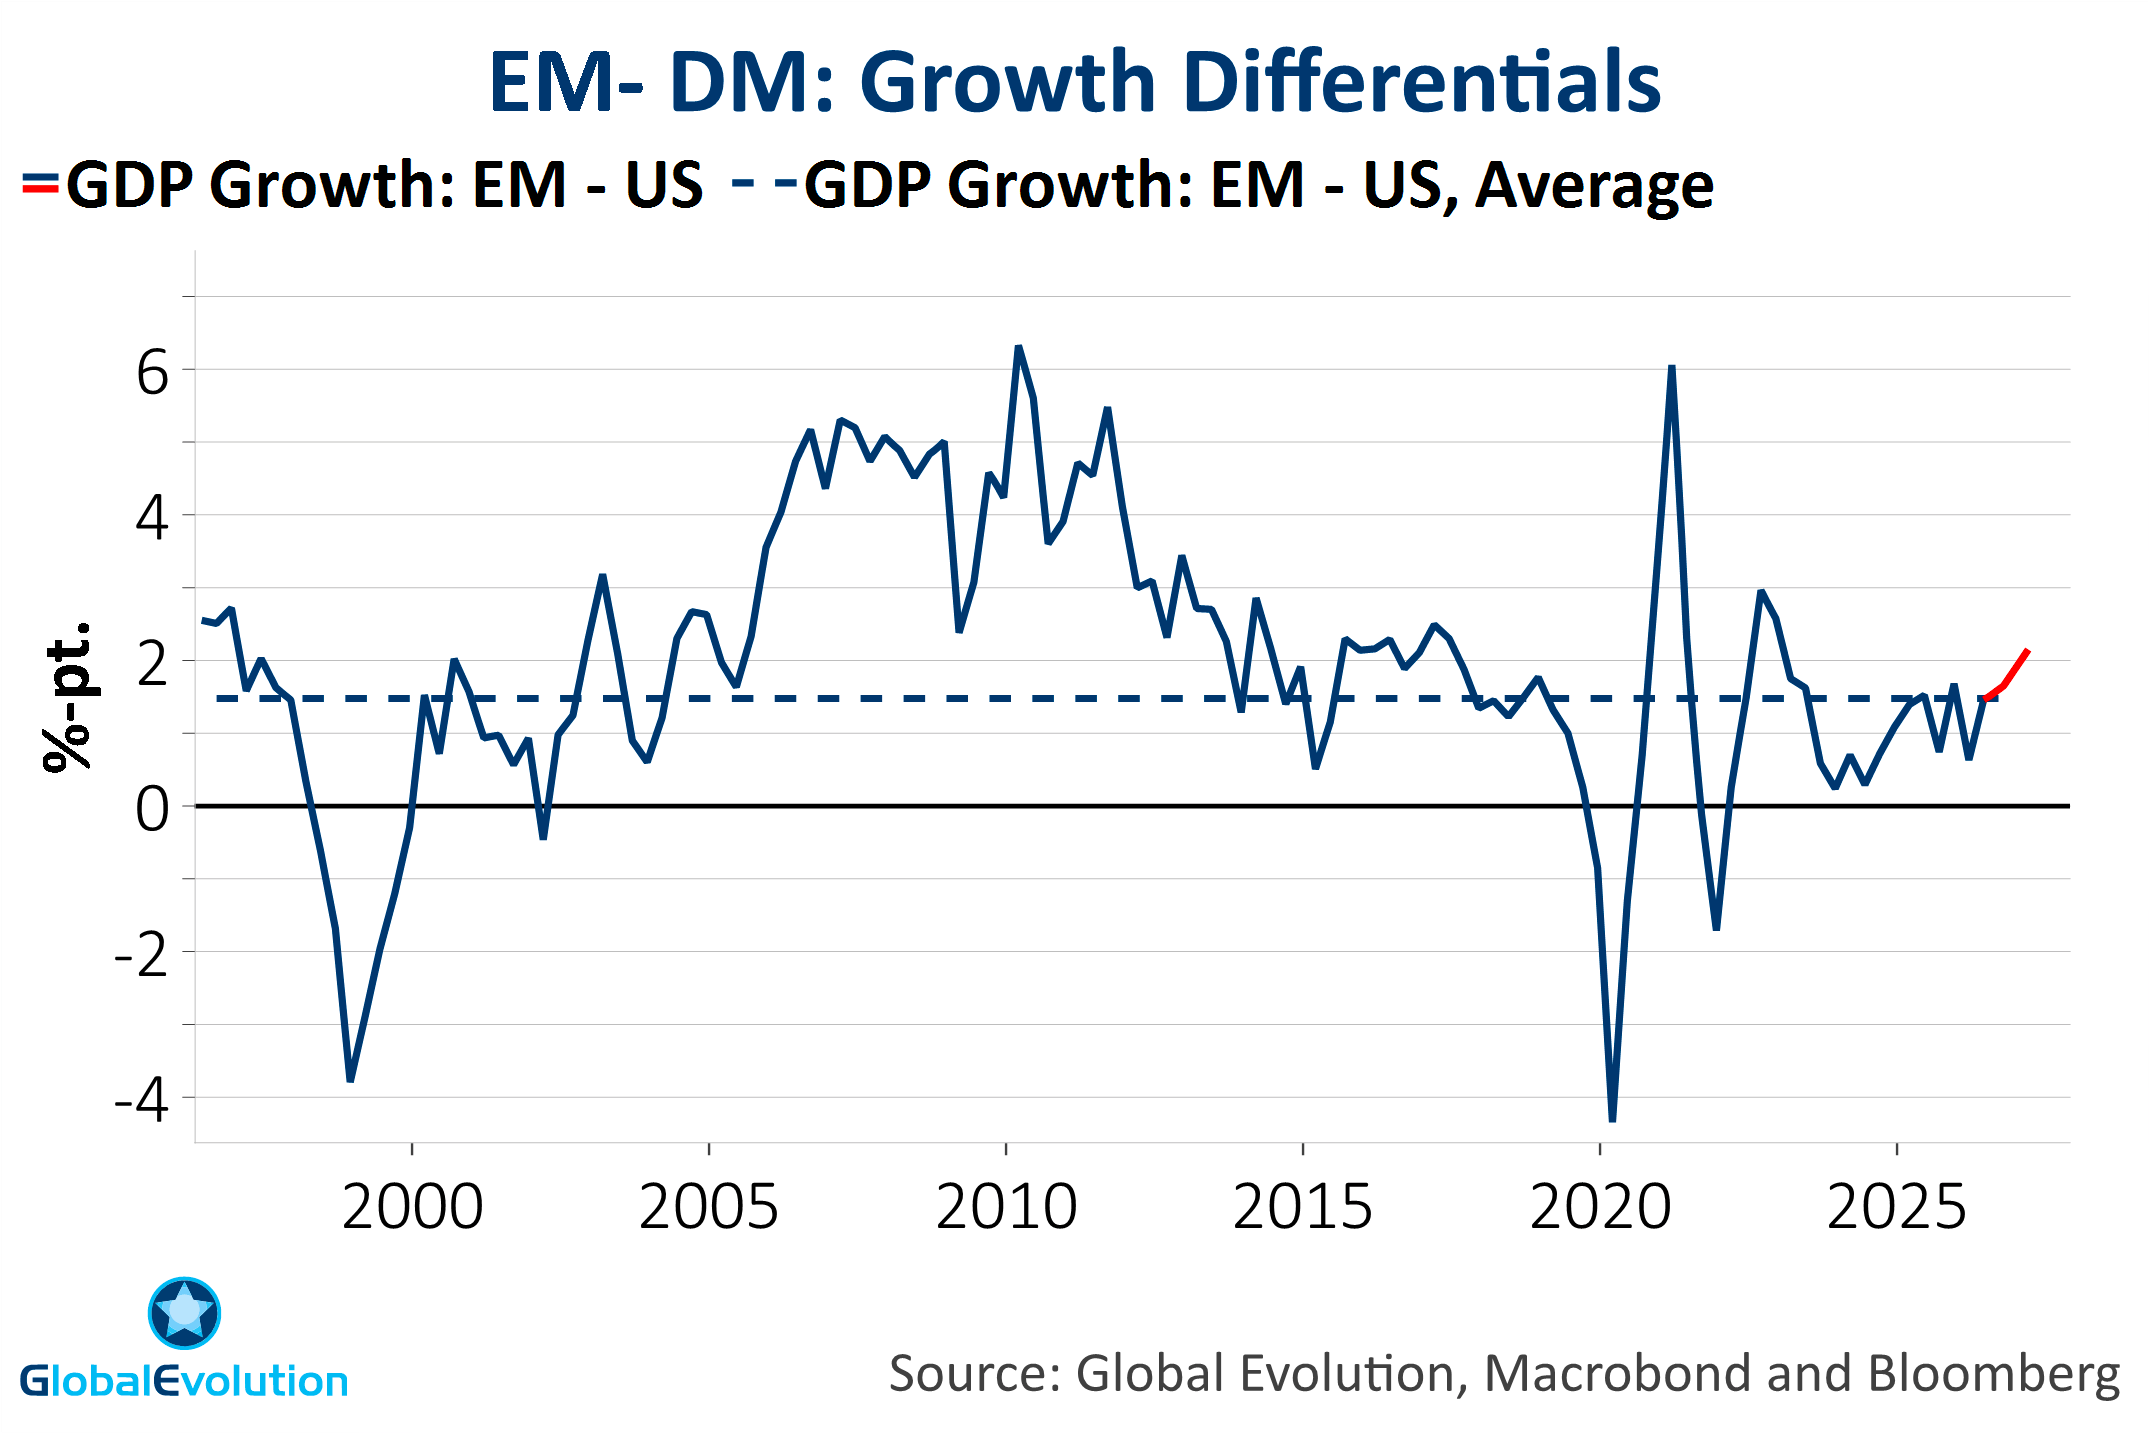
Gradual slowdown. Cyclical backdrop resilient but more volatile. Rate risk morphs into credit risk. EM–US growth gap widening (chart).
Inflation
Disinflationary trend intact. Geopolitical risks peak ahead of the midterms. Reversaal of energy price spike delayed, not derailed.
Policy
Moderate monetary headwinds prevail but Fed hikes are overpriced. Lower leg of the K (consumers) outweigh inflationary impact of upper leg (AI).
Key Macro Risk
The AI innovation cycle: euphoria extended, or a credit crunch amid an issuance wall, crowding out on other bond segments?
MARKETS: Muddling through, but volatility persists
Review
Our preference for local currency EMD played out well in Q3. A cautiously constructive stance on overall EMD risk proved too optimistic as monetary headwinds gathered pace in Q3.
Tactical horizon
Risk appetite to recover into year-end due to dovish Fed repricing and falling oil prices. Maintain an overweight in local EMD. Spread risk tilted to the upside as the credit cycle turns.
Strategic horizon
Global Evolution view: Expecting solid carry-driven returns. Preference to shift towards hard currency EMD as duration turns into a tailwind. Elevated vol argues for a tactical approach.
The upper leg of the K
Investments, the swing factor of the business cycle, remain the key driver of global growth.
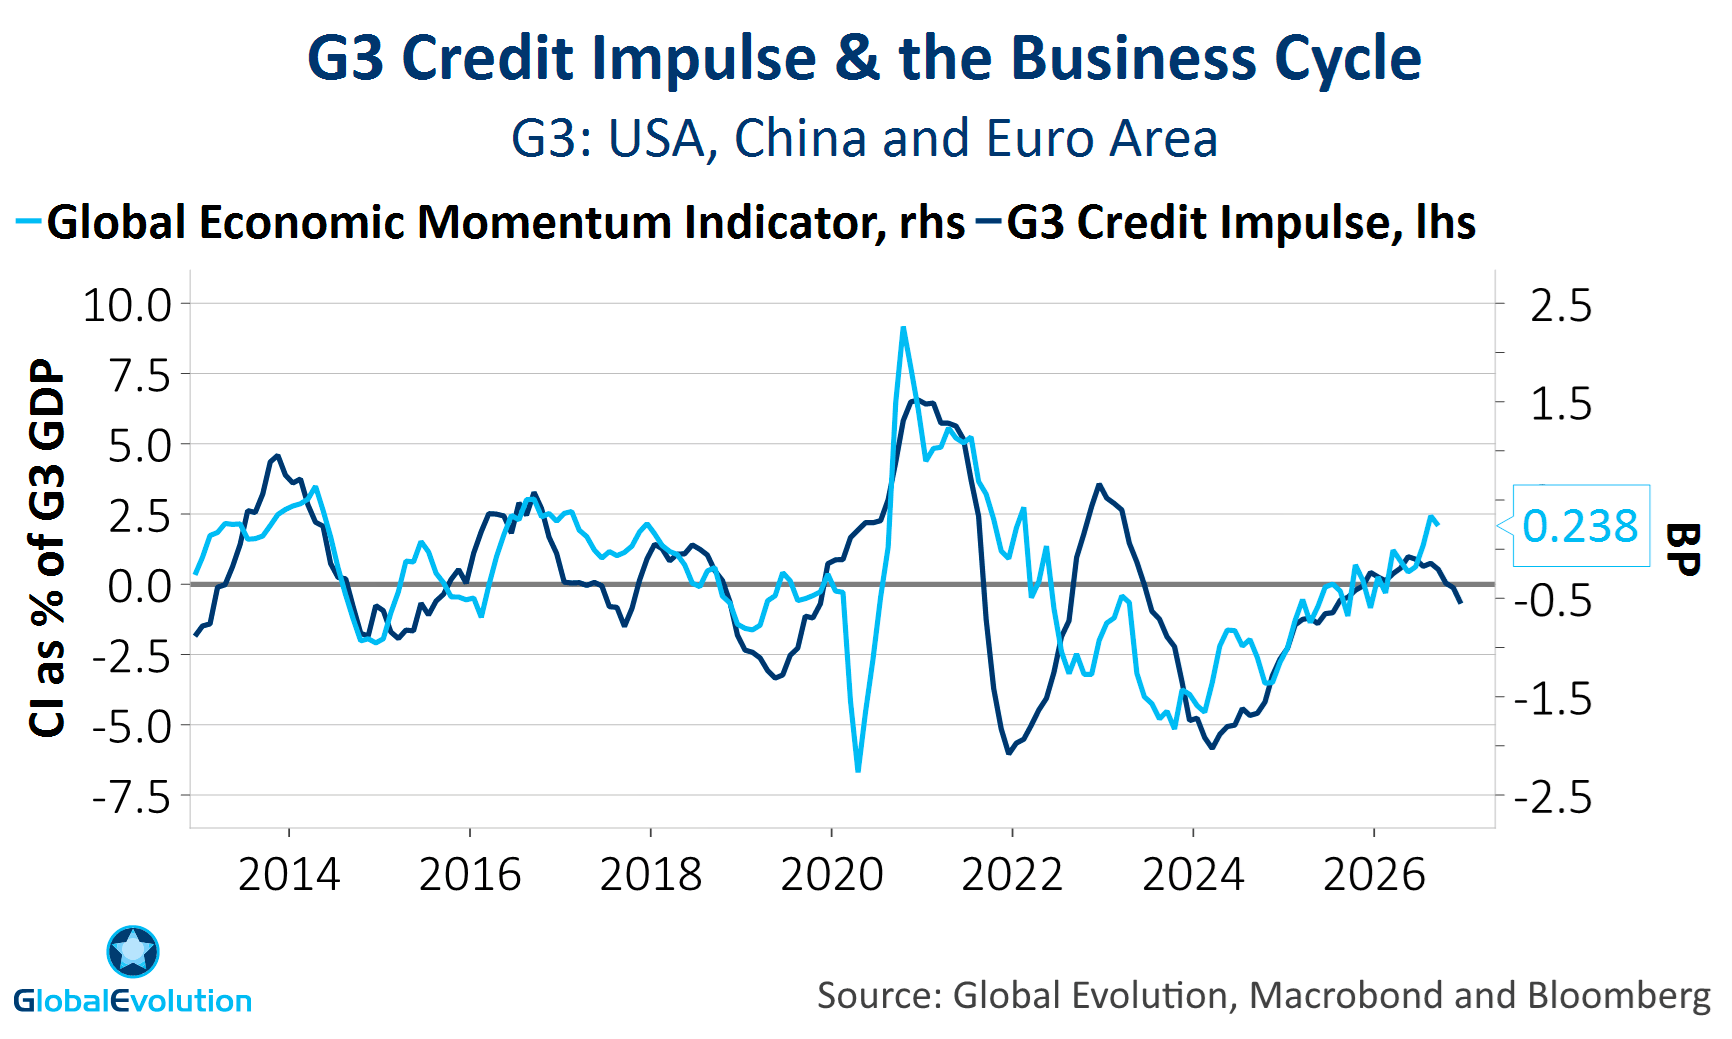
Growth cycle as good as it gets
A gradual turn in the credit cycle is confirmed, as past monetary easing fades and the real rate spike begins to bite.
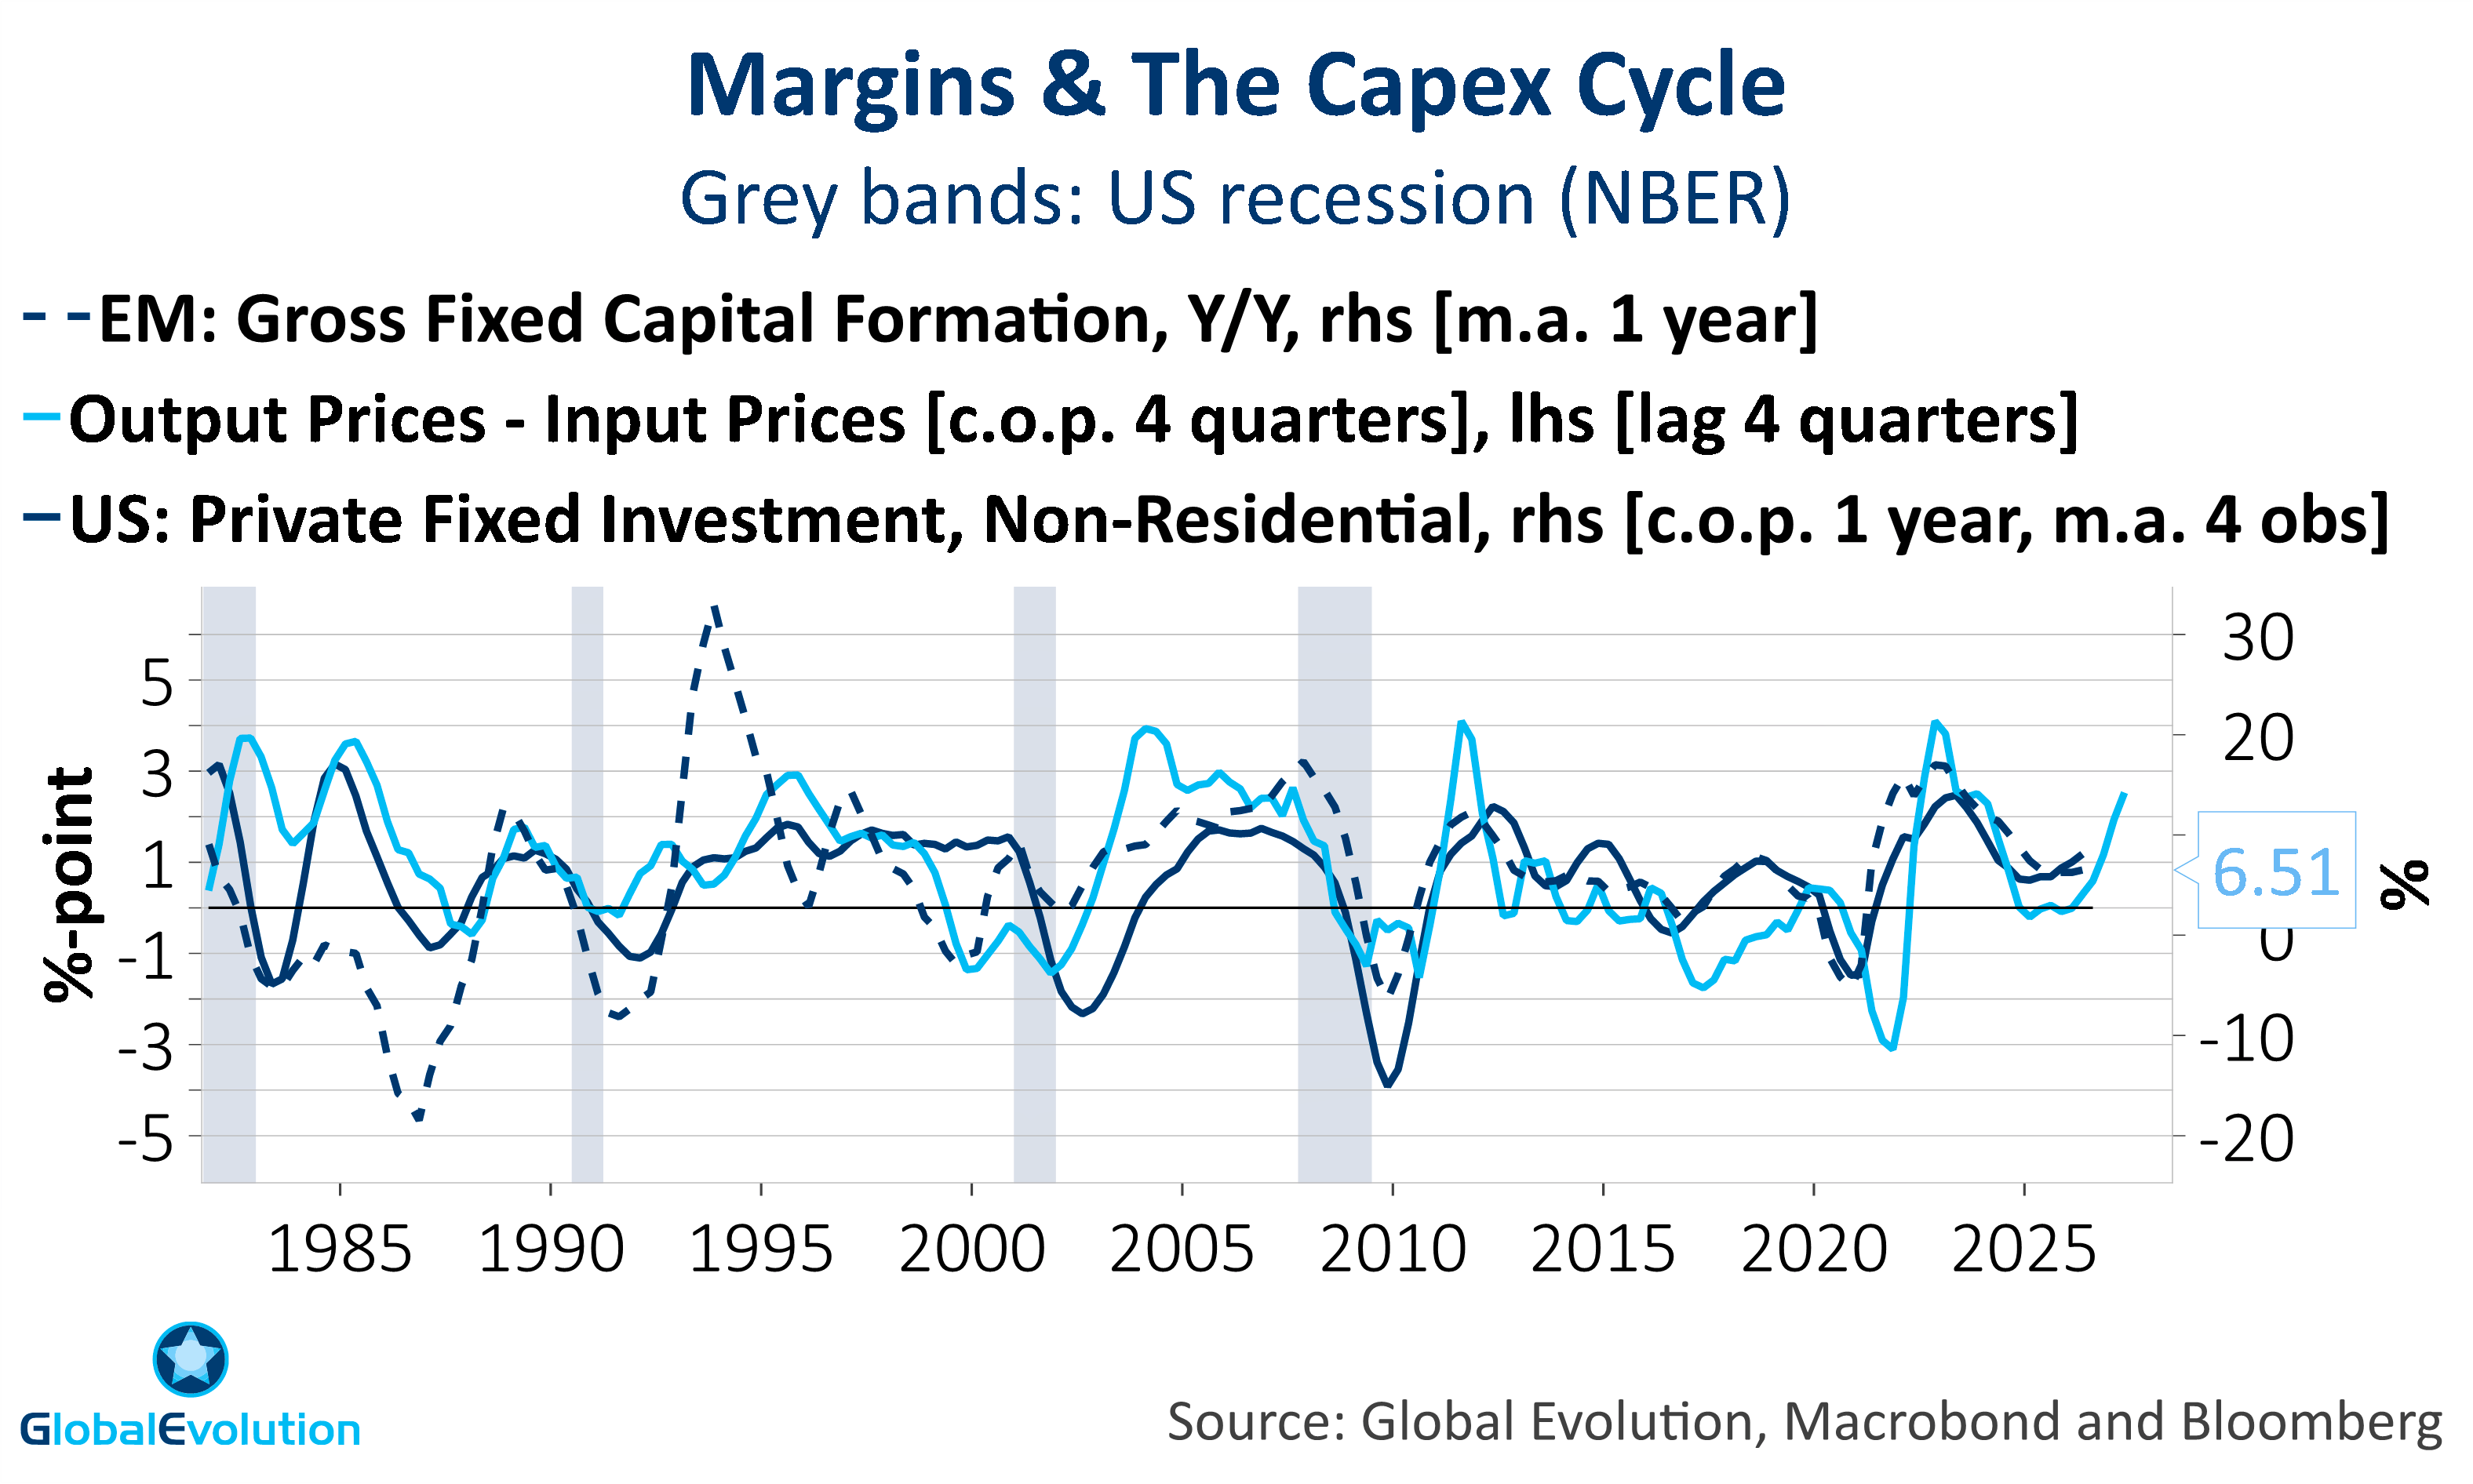
AI capex cycle intact
Strong margins signal sustained strength in the AI-driven global capex cycle.
US cushion wearing thin
Declining savings & wealth creation have cushioned US households. This can only run so far.
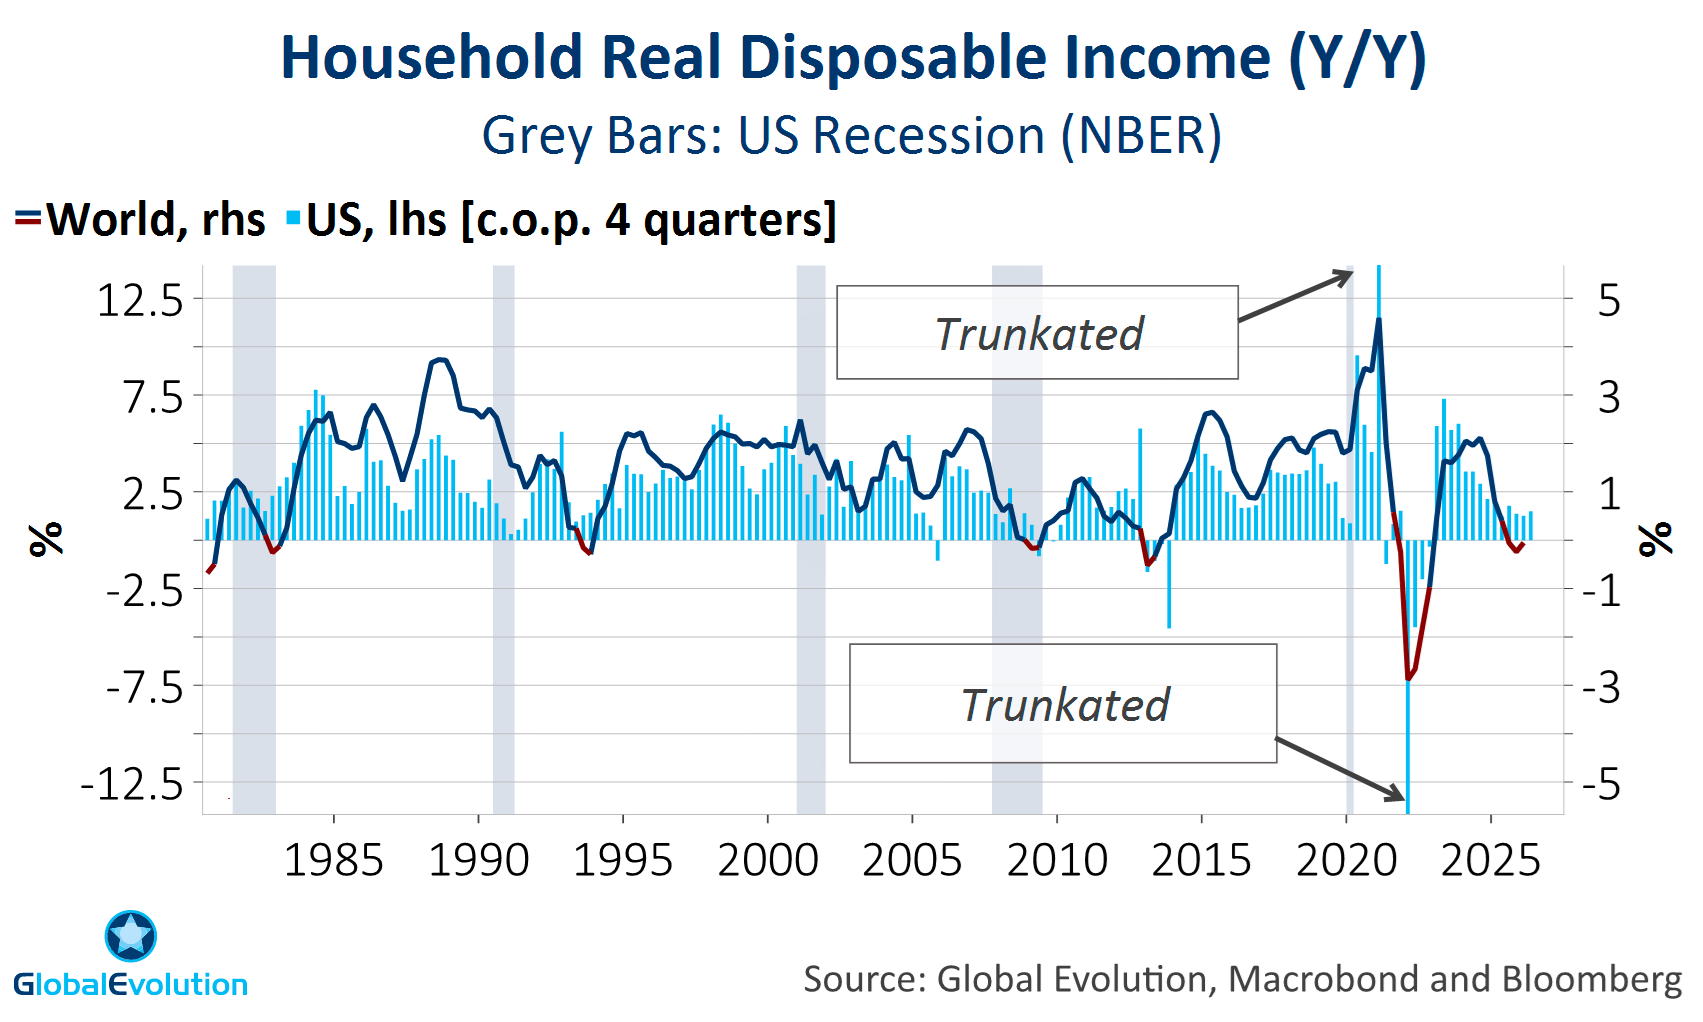
The weak spot
Household income is under pressure from persistently high energy prices and declining wage growth.
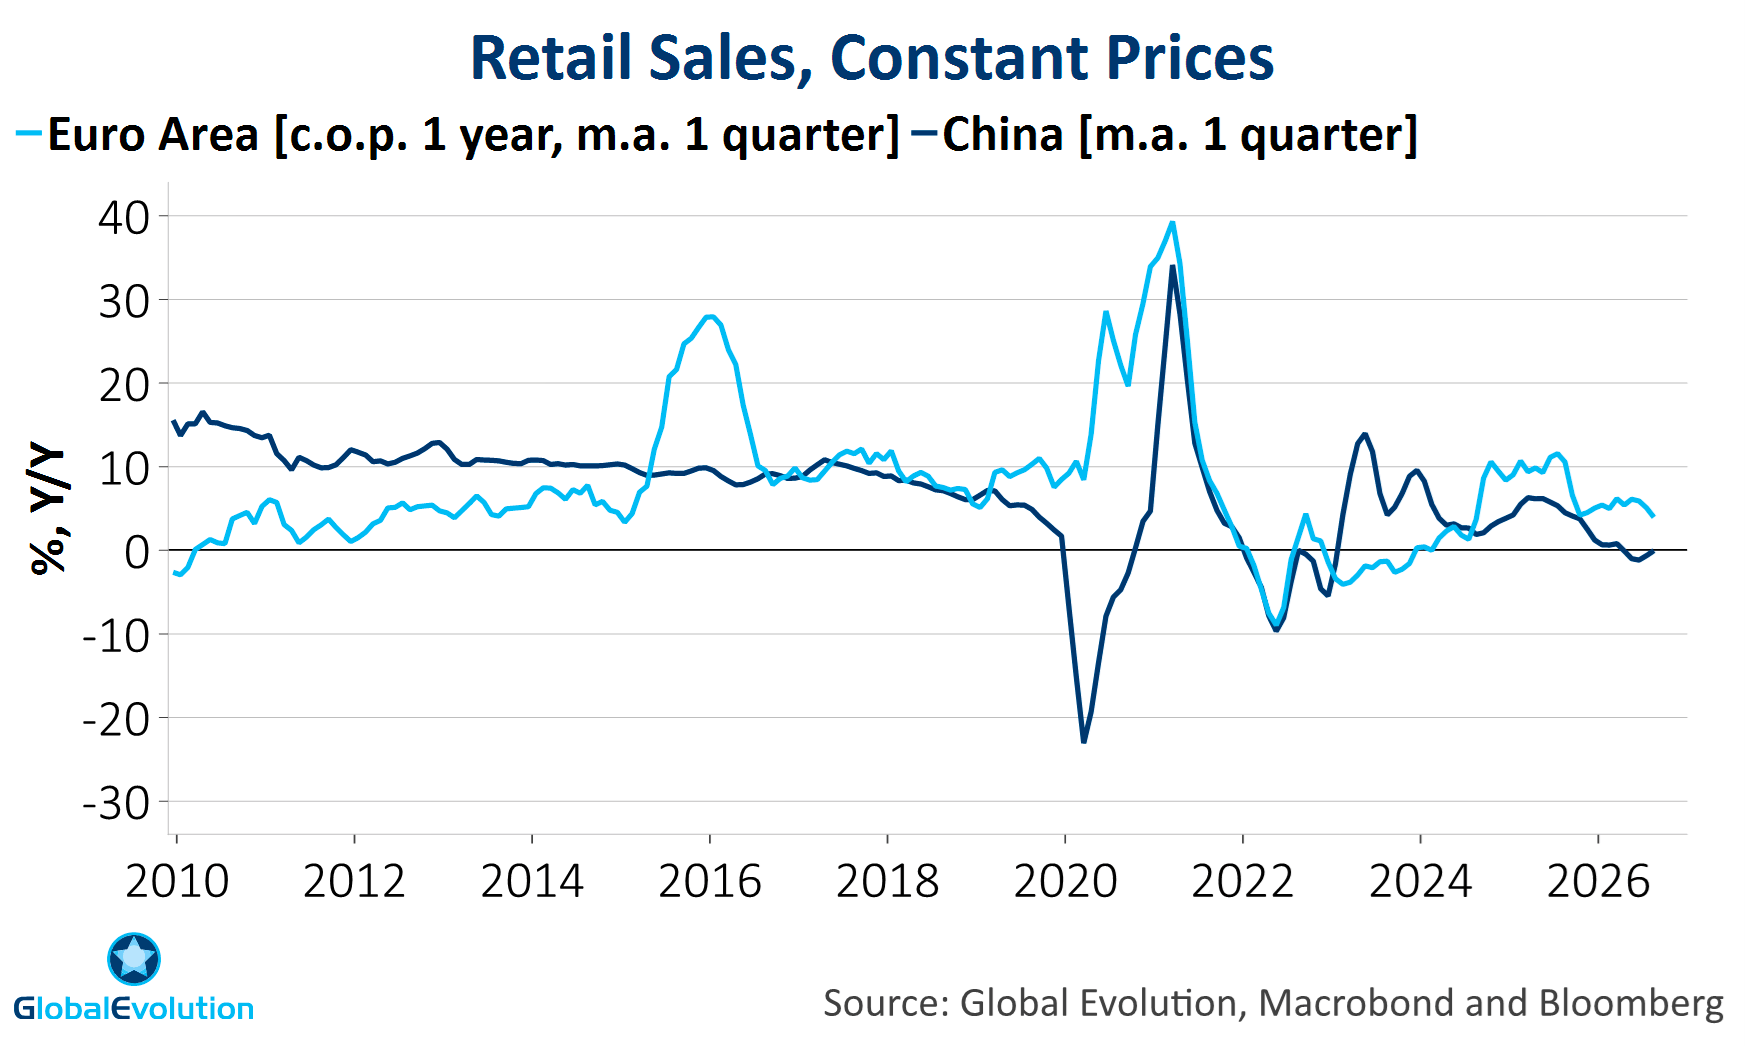
The lower leg of the K
We expect household demand to be the weak spot, causing global growth to slow.
A silver lining
The lower leg of the K limits monetary tightening risks.
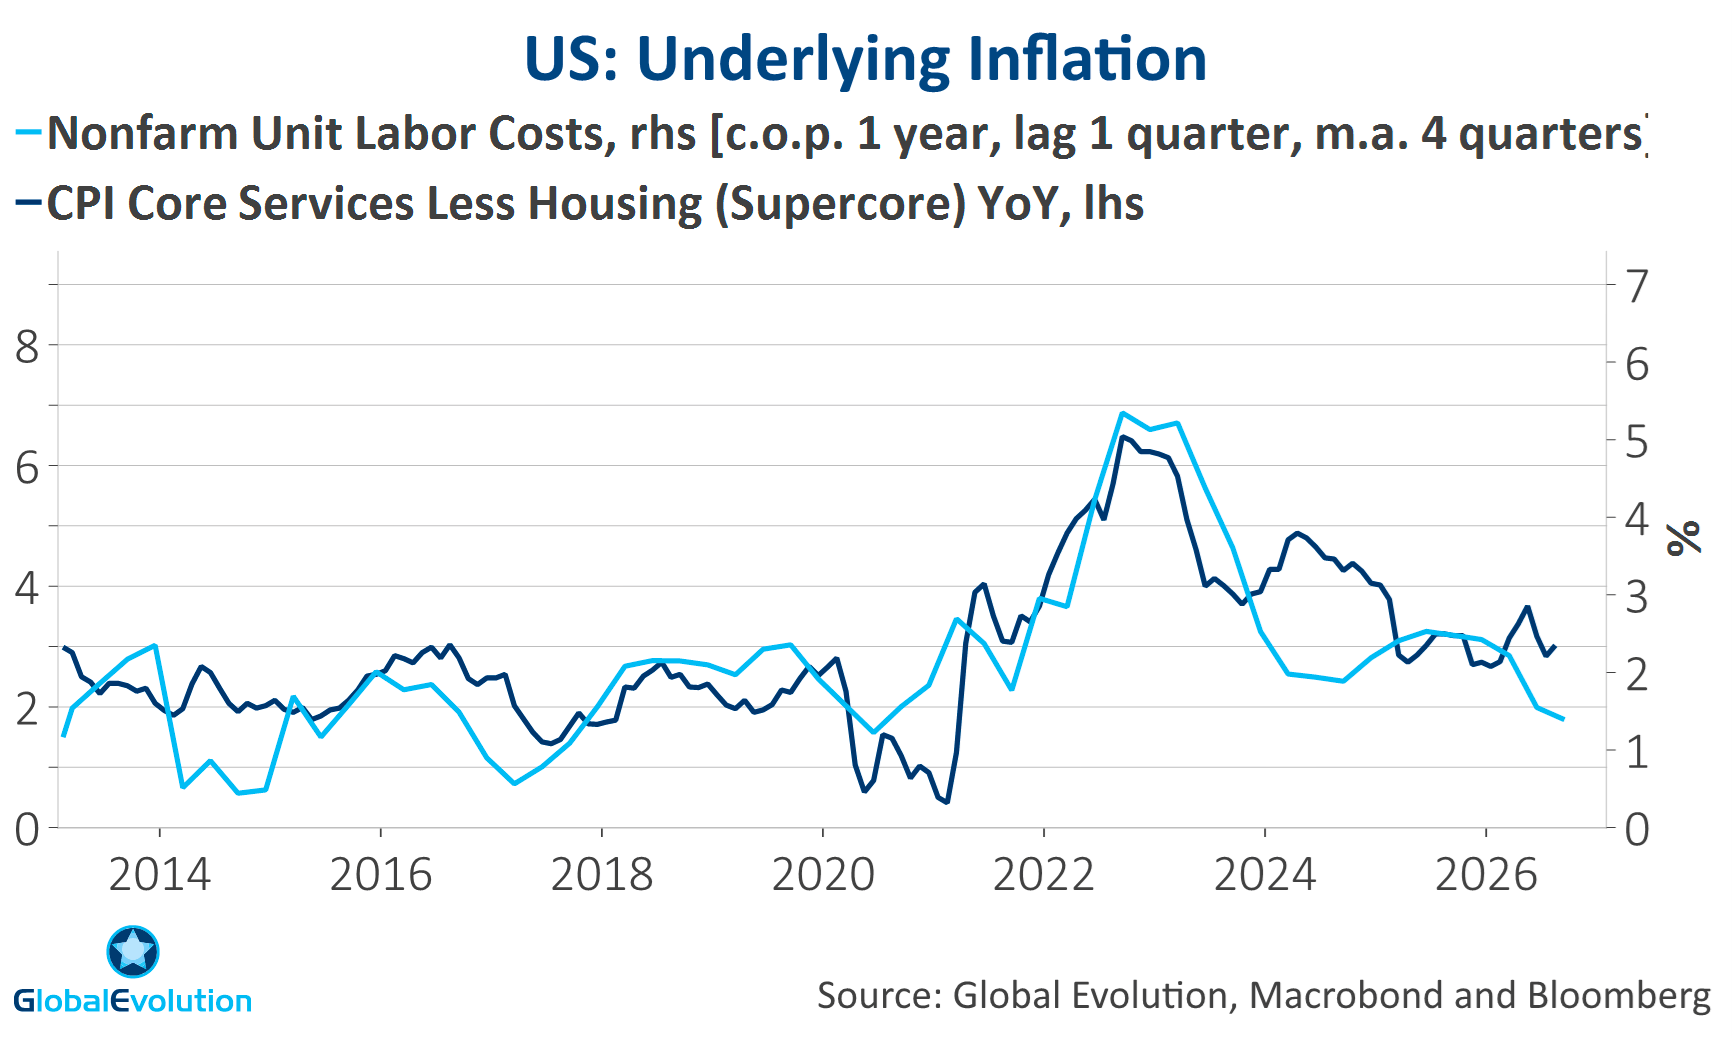
Underlying inflation falling
Despite persistently high energy prices, underlying US inflation is trending down. The mother of all central bank fears (2nd round effects) is not materializing.
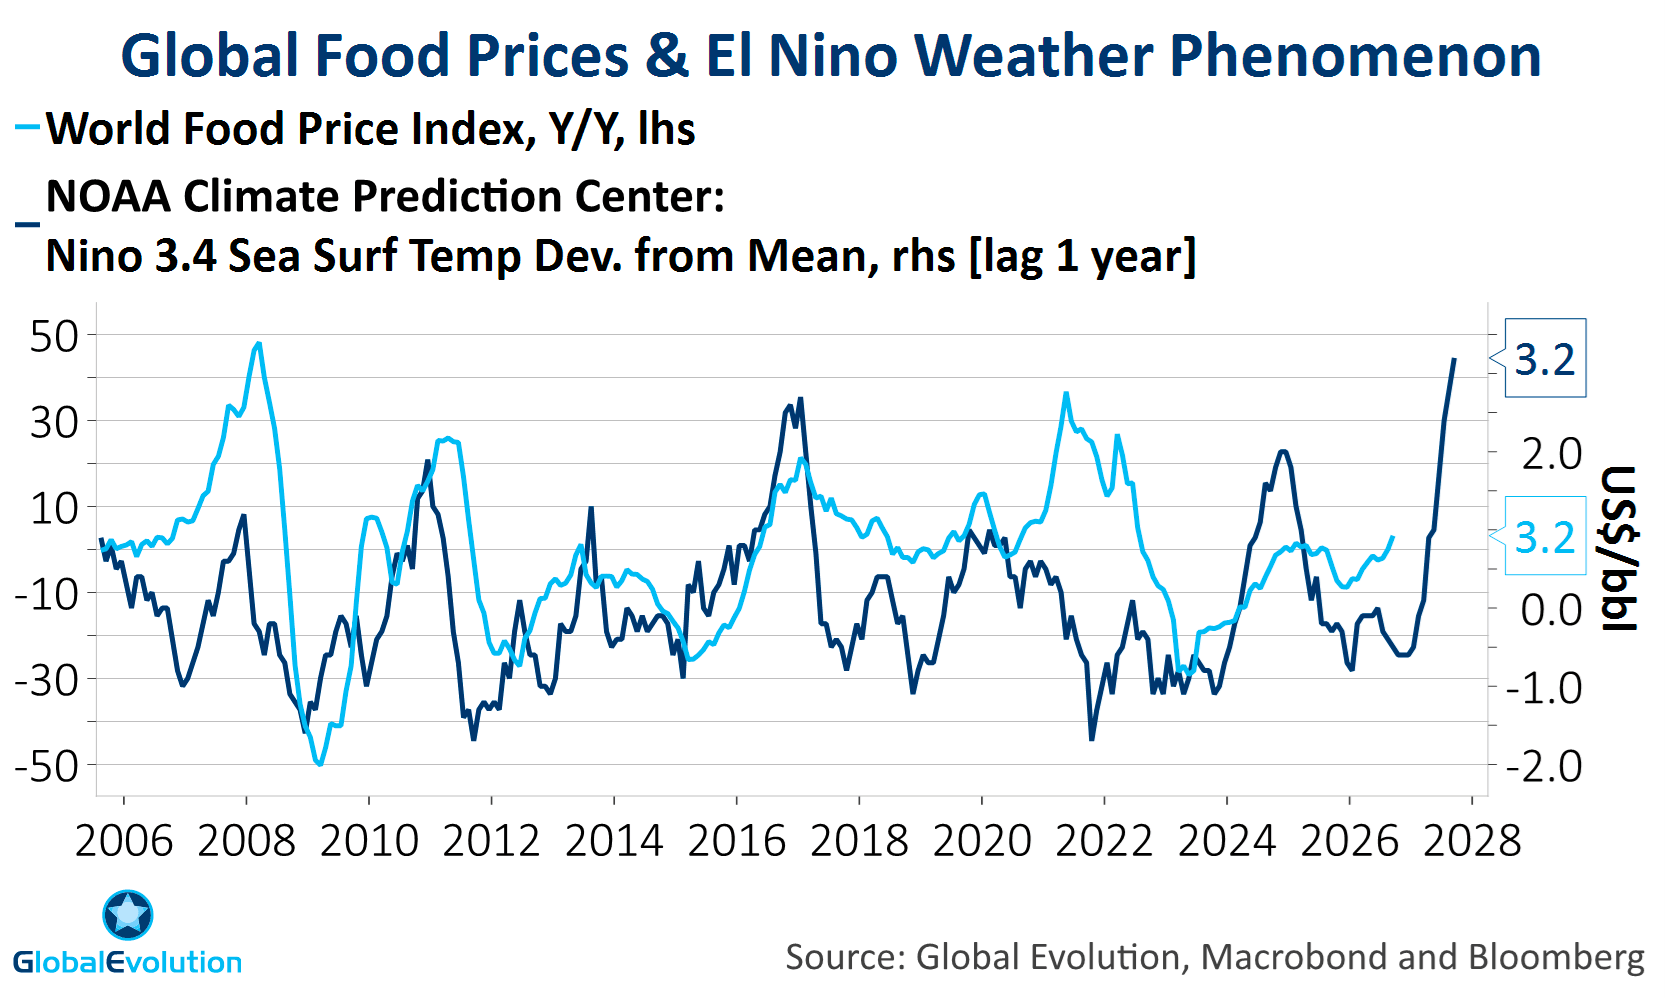
EM angle: El Niño vs. structural improvements
El Niño poses upward pressure on headline inflation over the coming months. Medium-term, the EM-DM inflation gap will likely remain historically tight as energy pass-through to EM inflation has declined.
Impulse set to fade
The inflationary impulse from tariffs and energy is set to fade in H2.
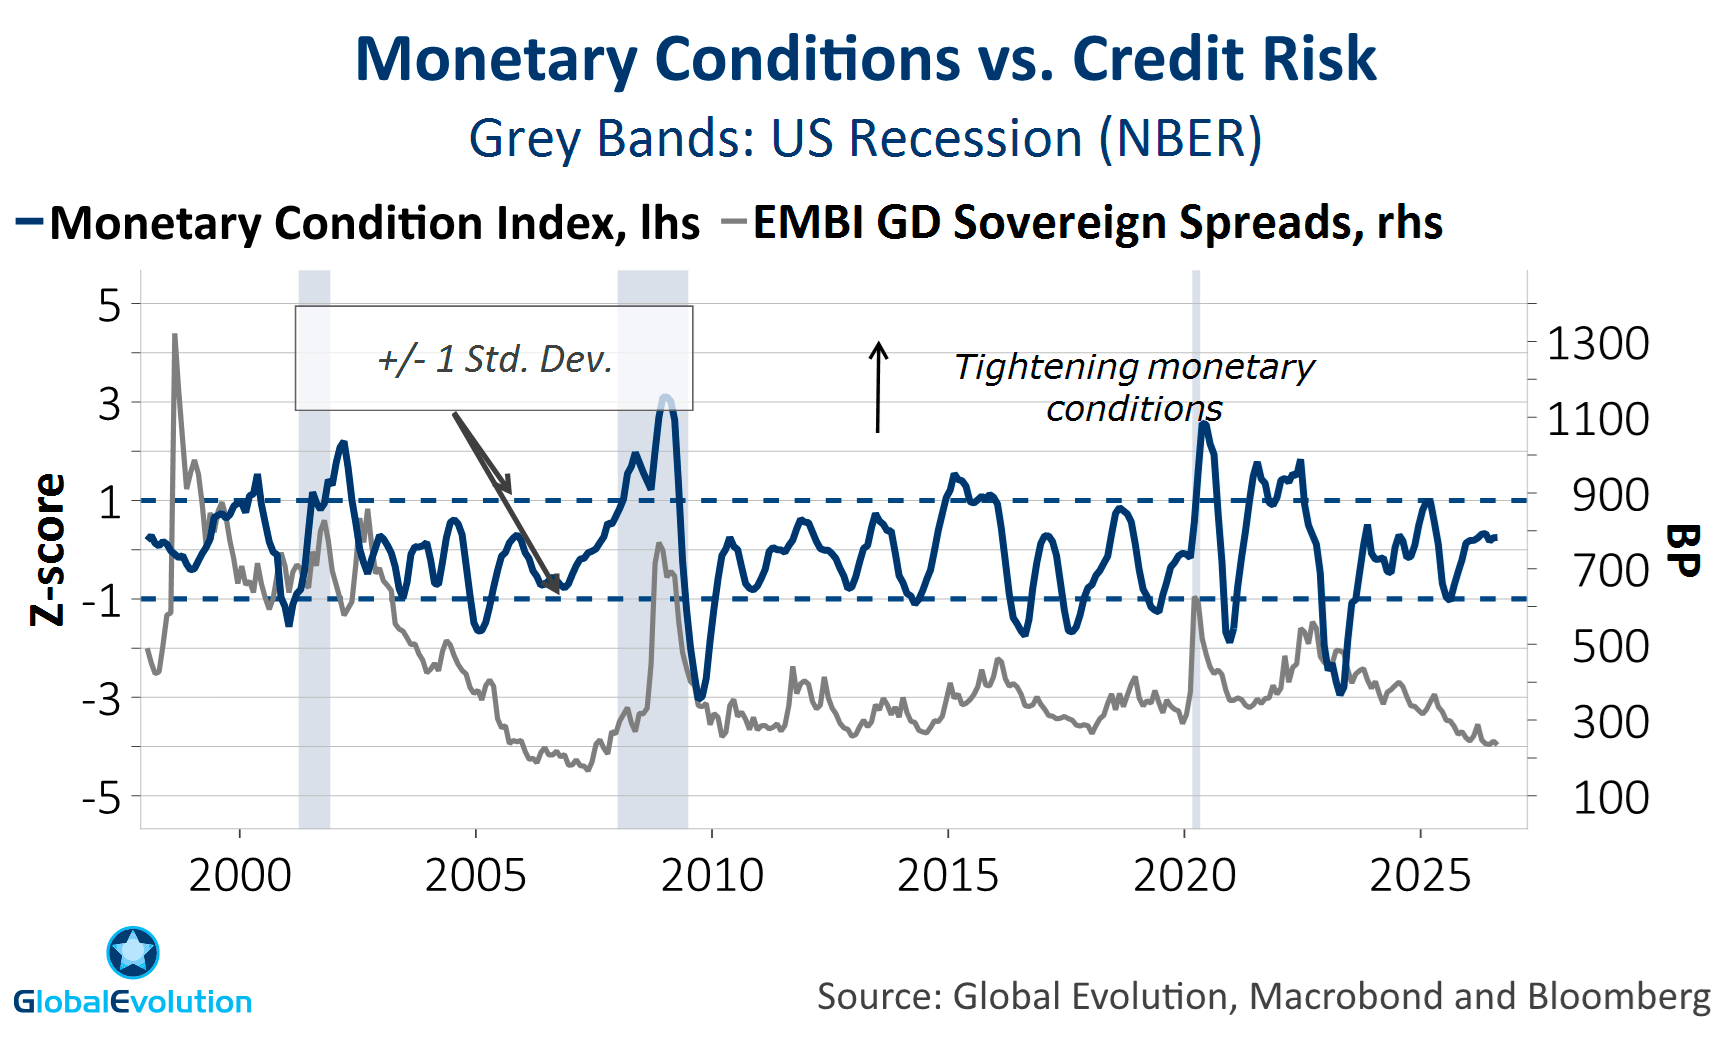
Tightening as expected
Late-cycle tightening plays out largely as expected. We expect one more Fed hike over 12M.
Manageable
A game-changer vs. 2025, but tightening stays < 1 std. dev., not enough to put the cycle at risk.
K-shape prevents over-tightening
Strength in the upper leg of the K is offset by weakness in the lower leg.
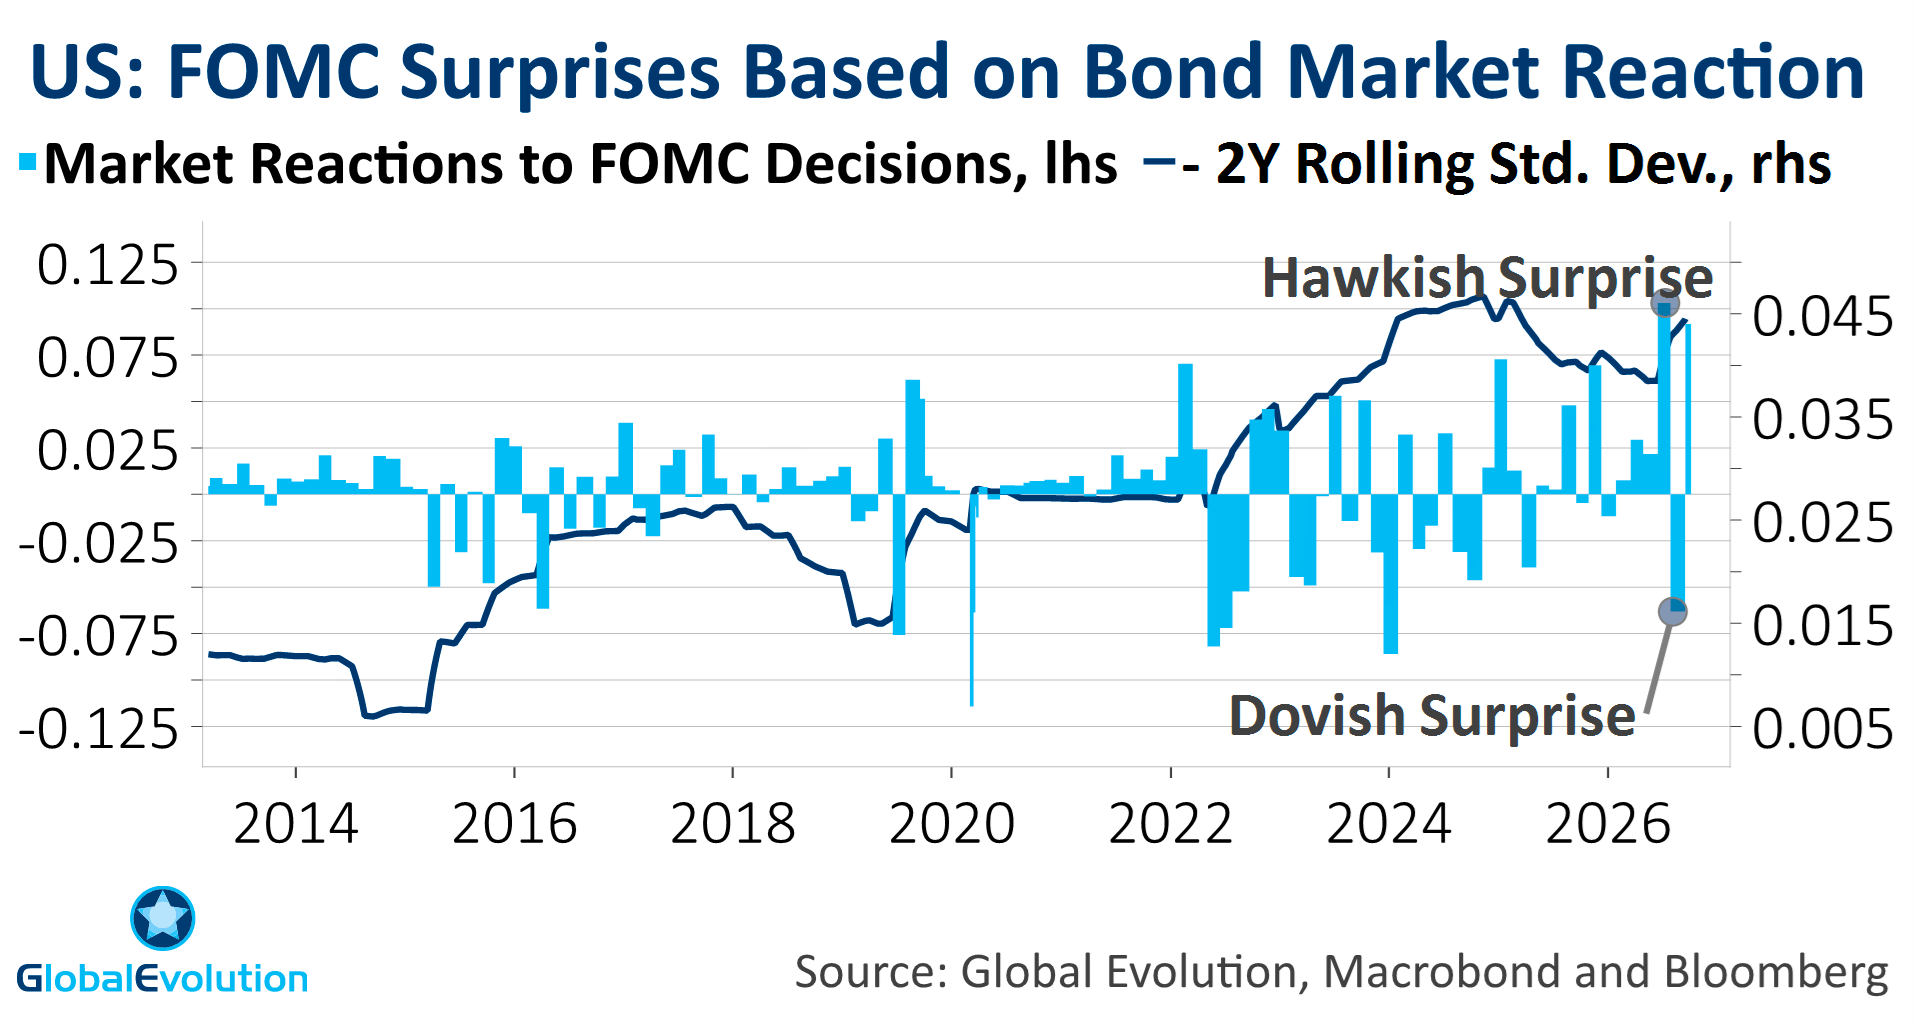
Source of volatility
That said, especially the Fed has induced volatility into the market place.
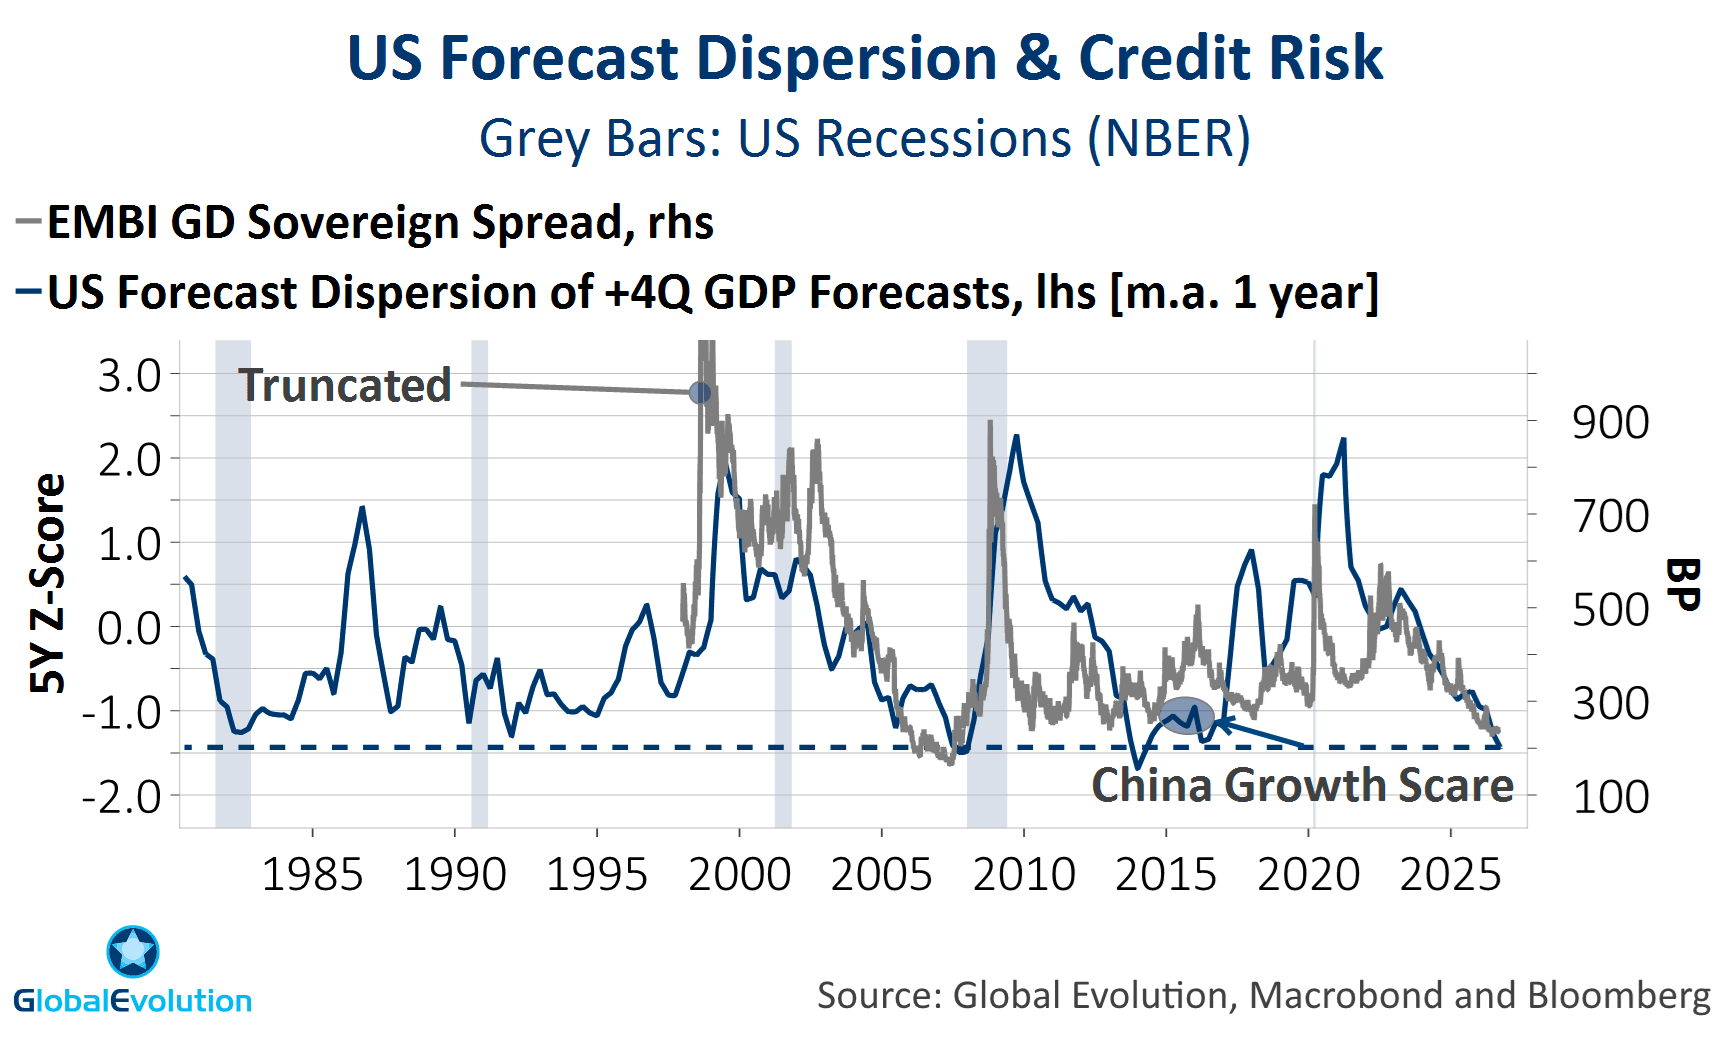
Late-cycle bellwethers
Monetary tightening, a turning credit cycle & a concentrated profit cycle (AI). Very low forecast dispersion suggests macro complacency.
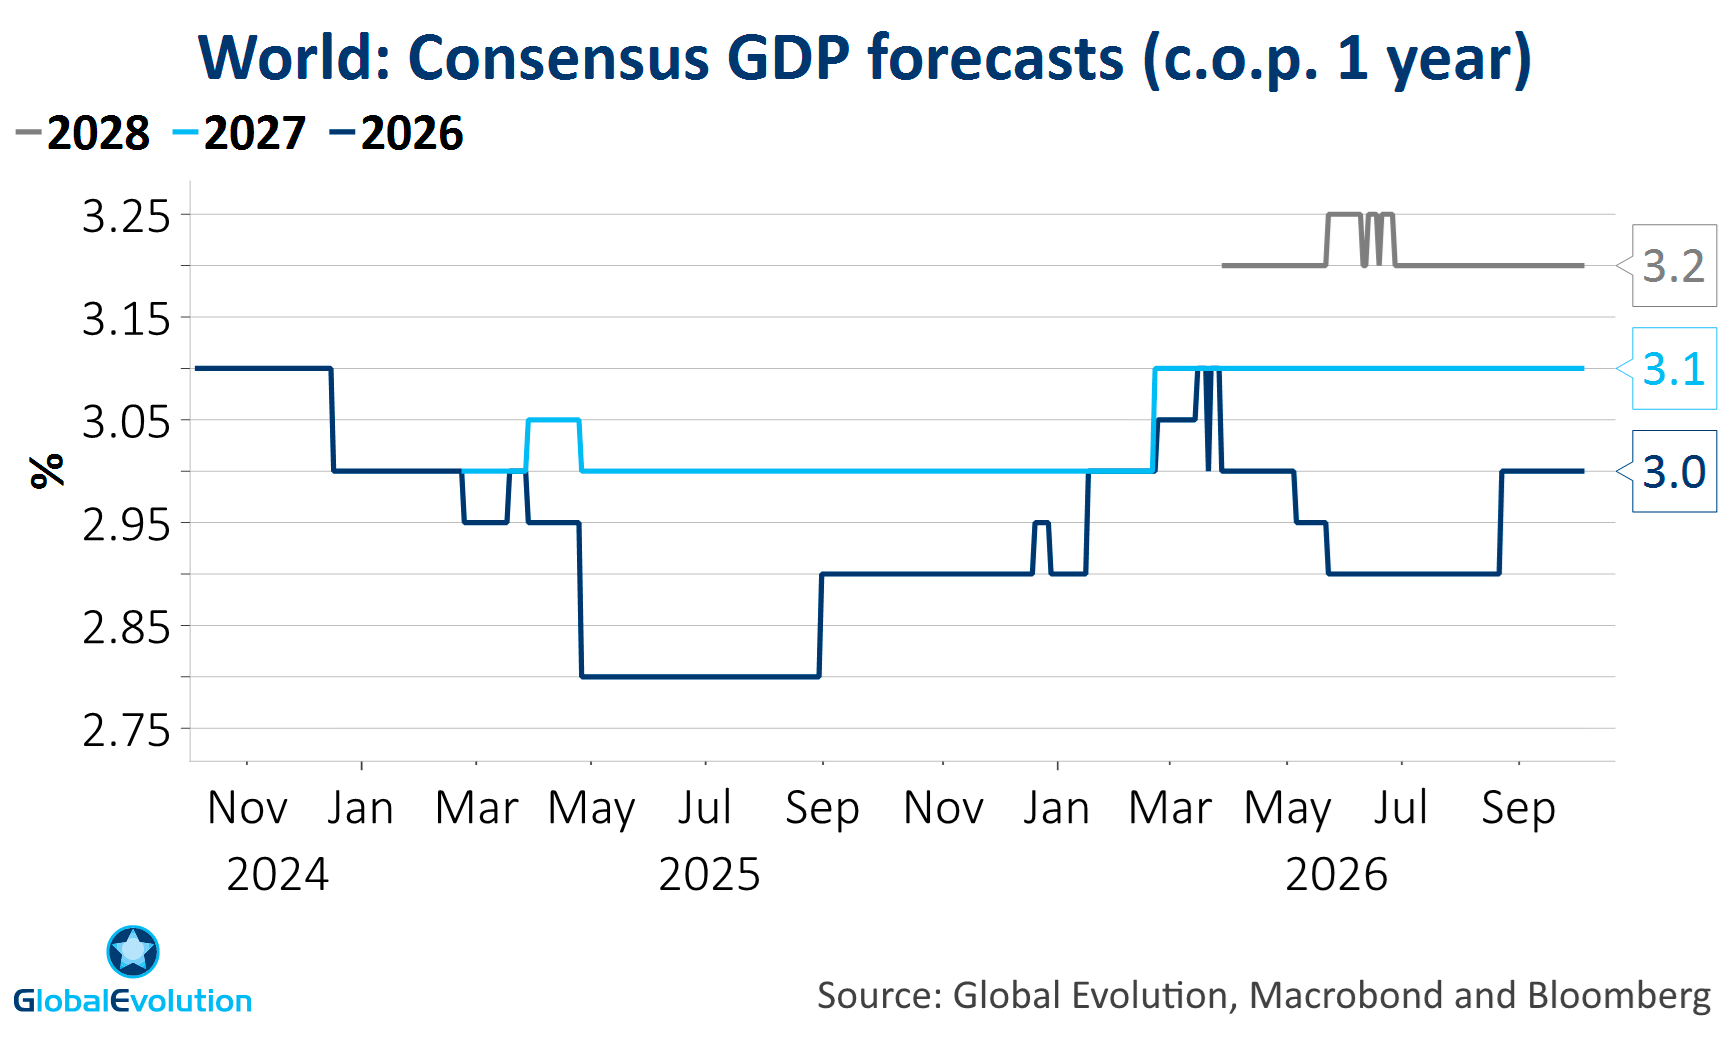
Herd behavior & recency bias
Analysts not only run in the same direction (first), they also expect the status quo to prevail (second).
Diversification is of the essence
However, a maturing cycle means a wider range of potential outcomes → diversification is of the essence, but harder to find!
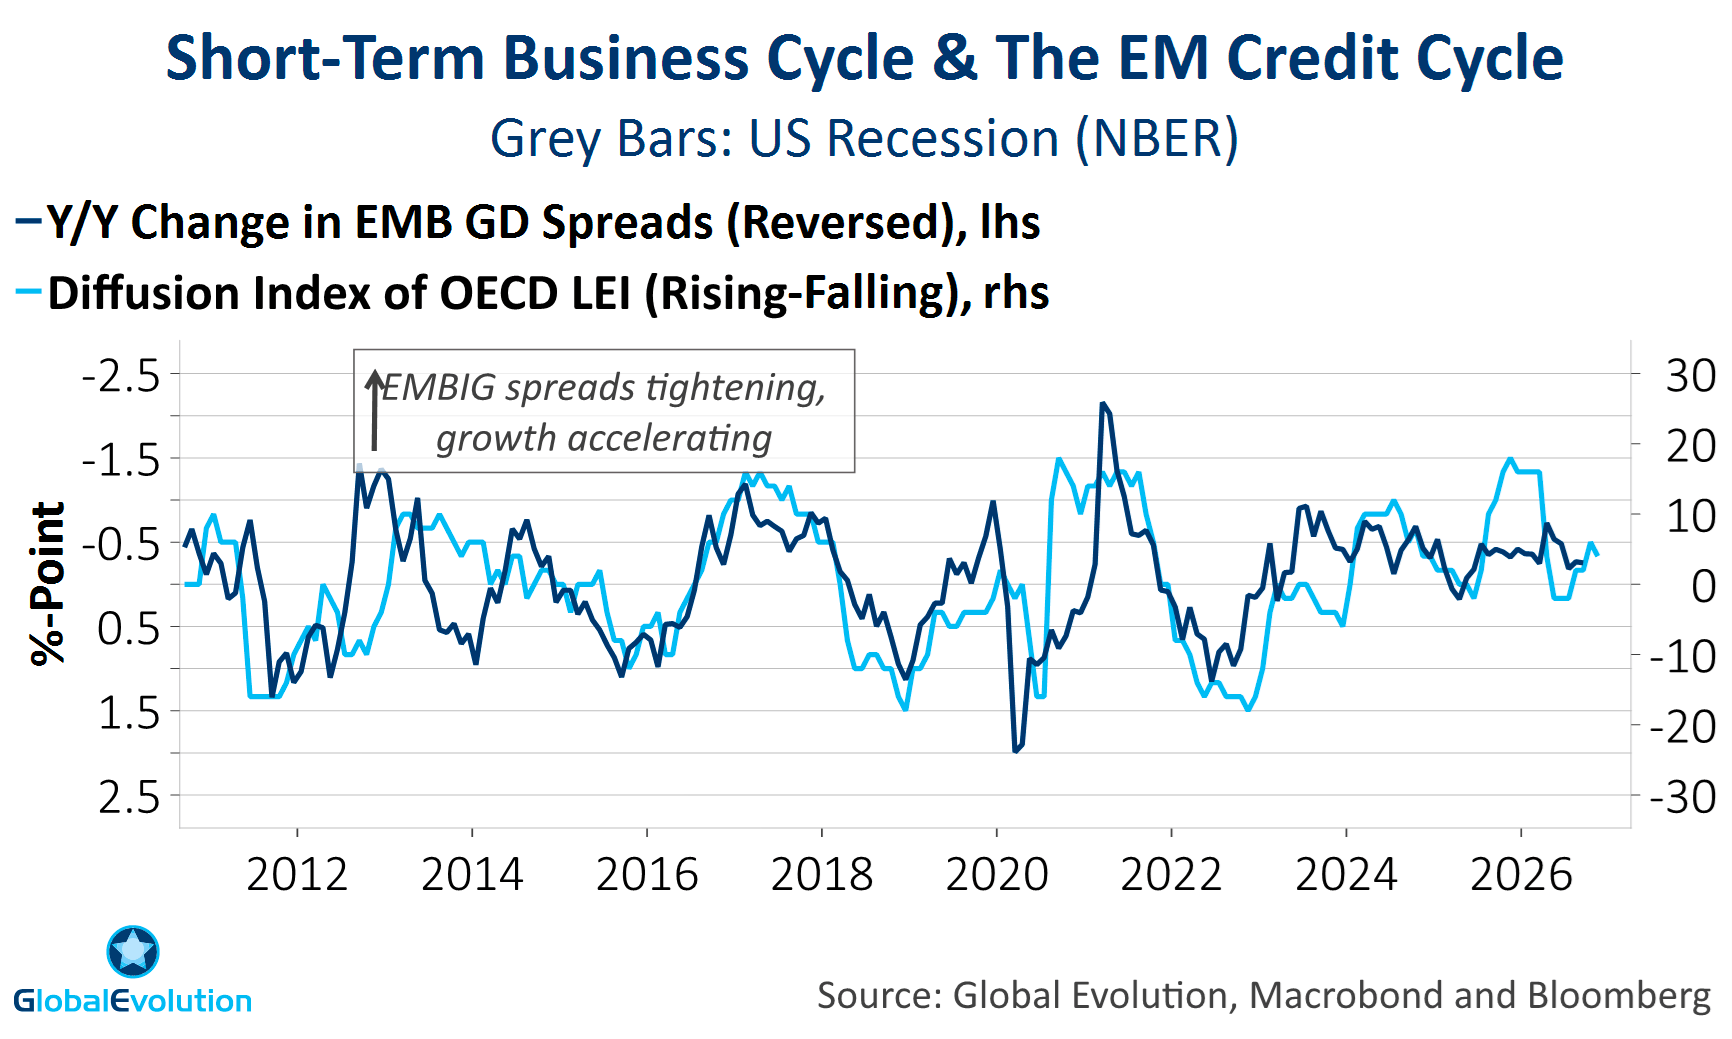
Fundamental risks
The macro backdrop remains resilient, for now mostly pointing towards stable spreads.
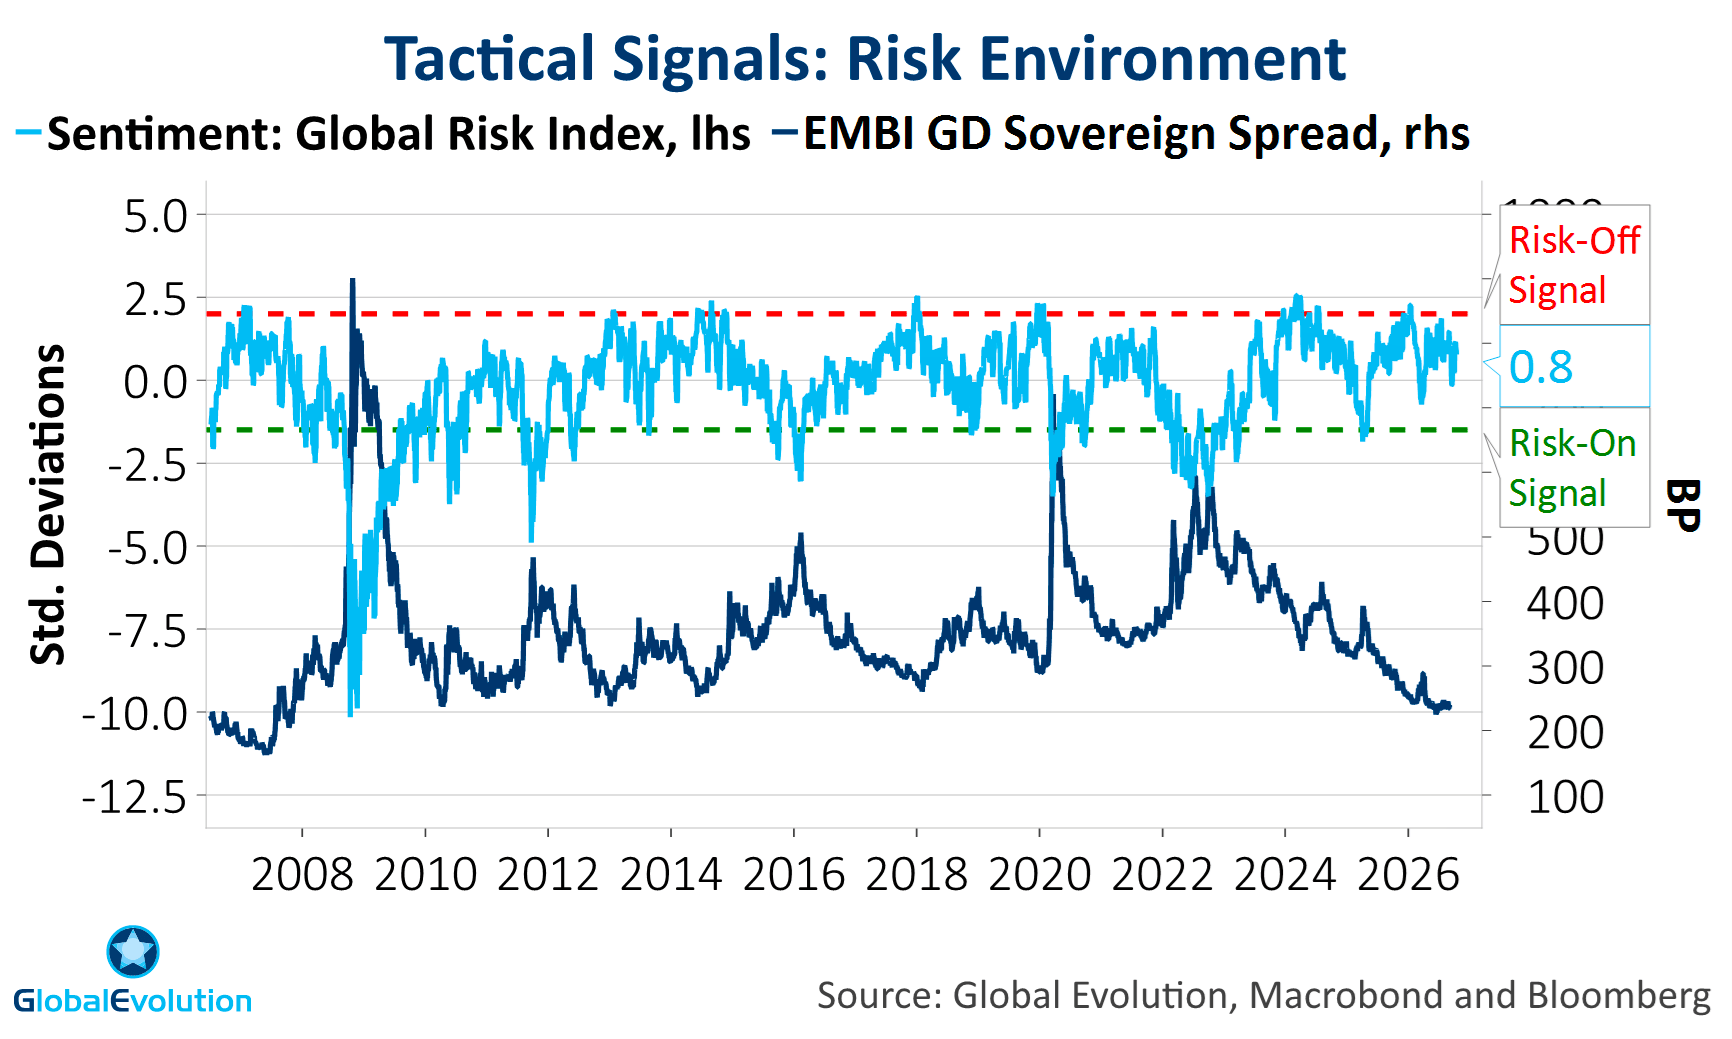
Sentiment hasn't cleared, yet
Sell signal in early 2026 and YTD returns close to flat. Continues to argue for a cautious approach to overall EMD risk.
Q4 rebound more likely than not
A better-than-even chance of a rebound in risk appetite, as Fed & ECB hikes are over-priced and the rate shock peaks.
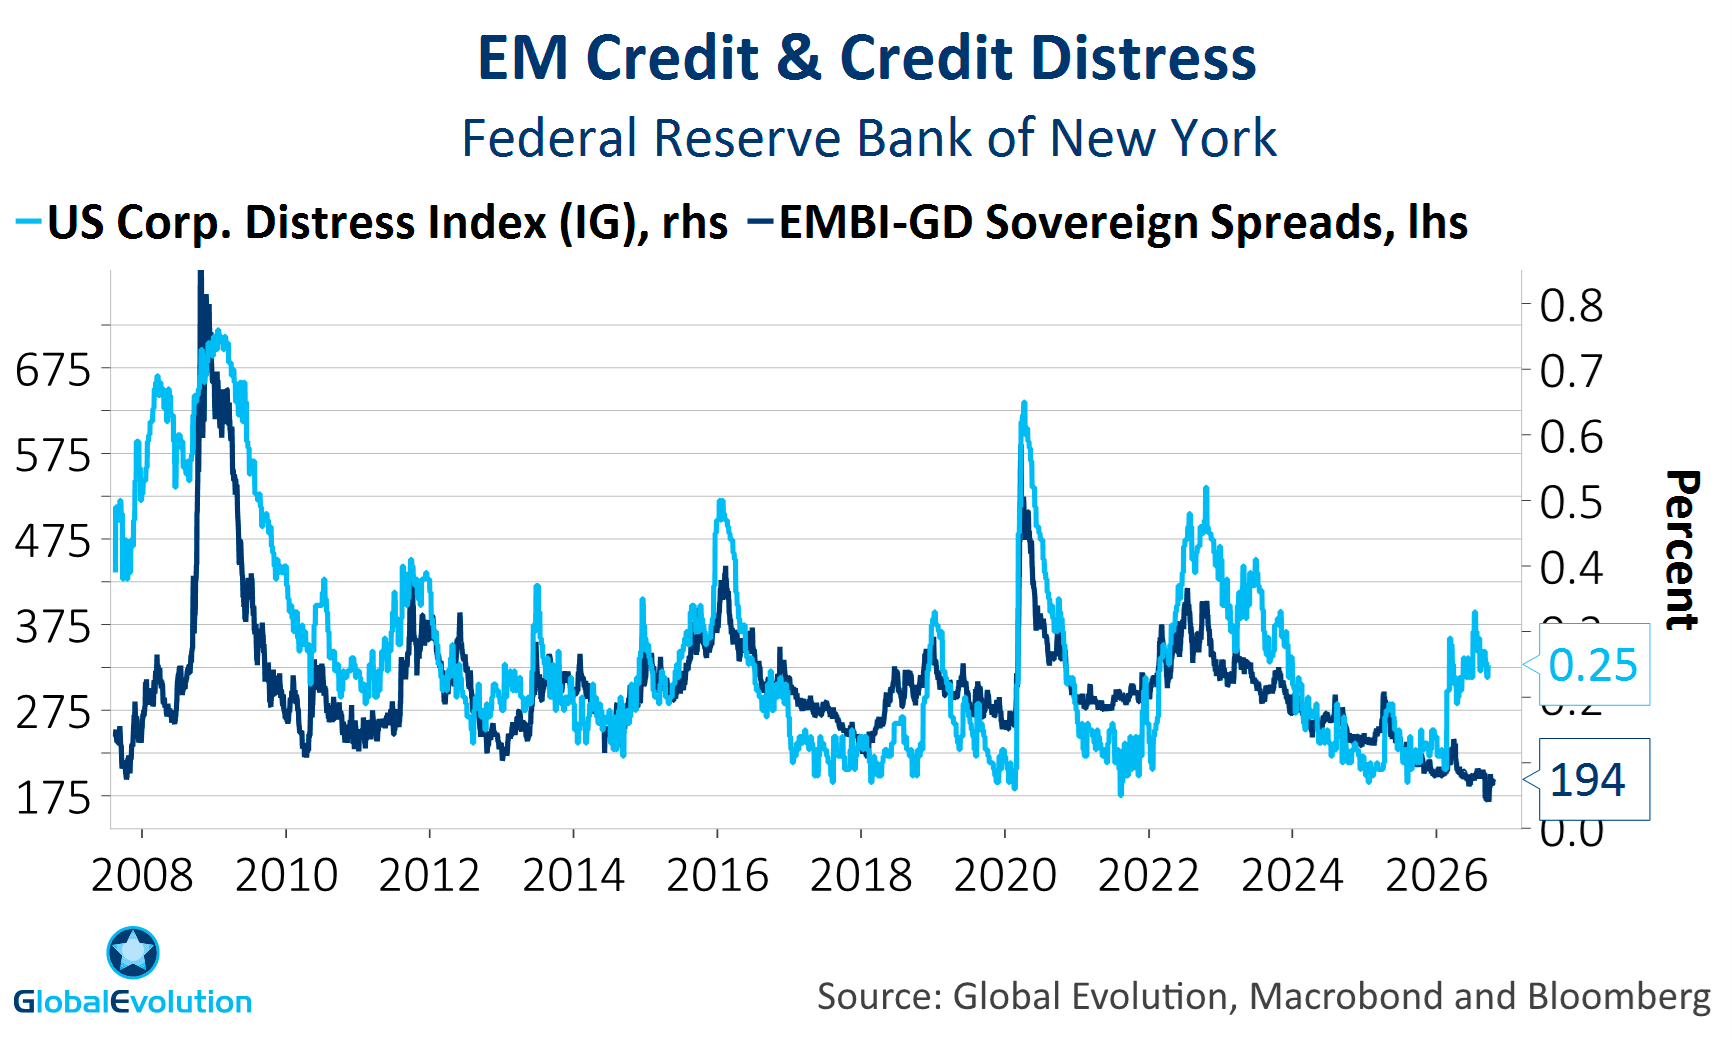
Credit risk:
Global Evolution view: Monetary tightening and the resulting rate risk are now cascading into credit risk. A maturing credit cycle and heavy DM issuance spell moderate spread widening risk.
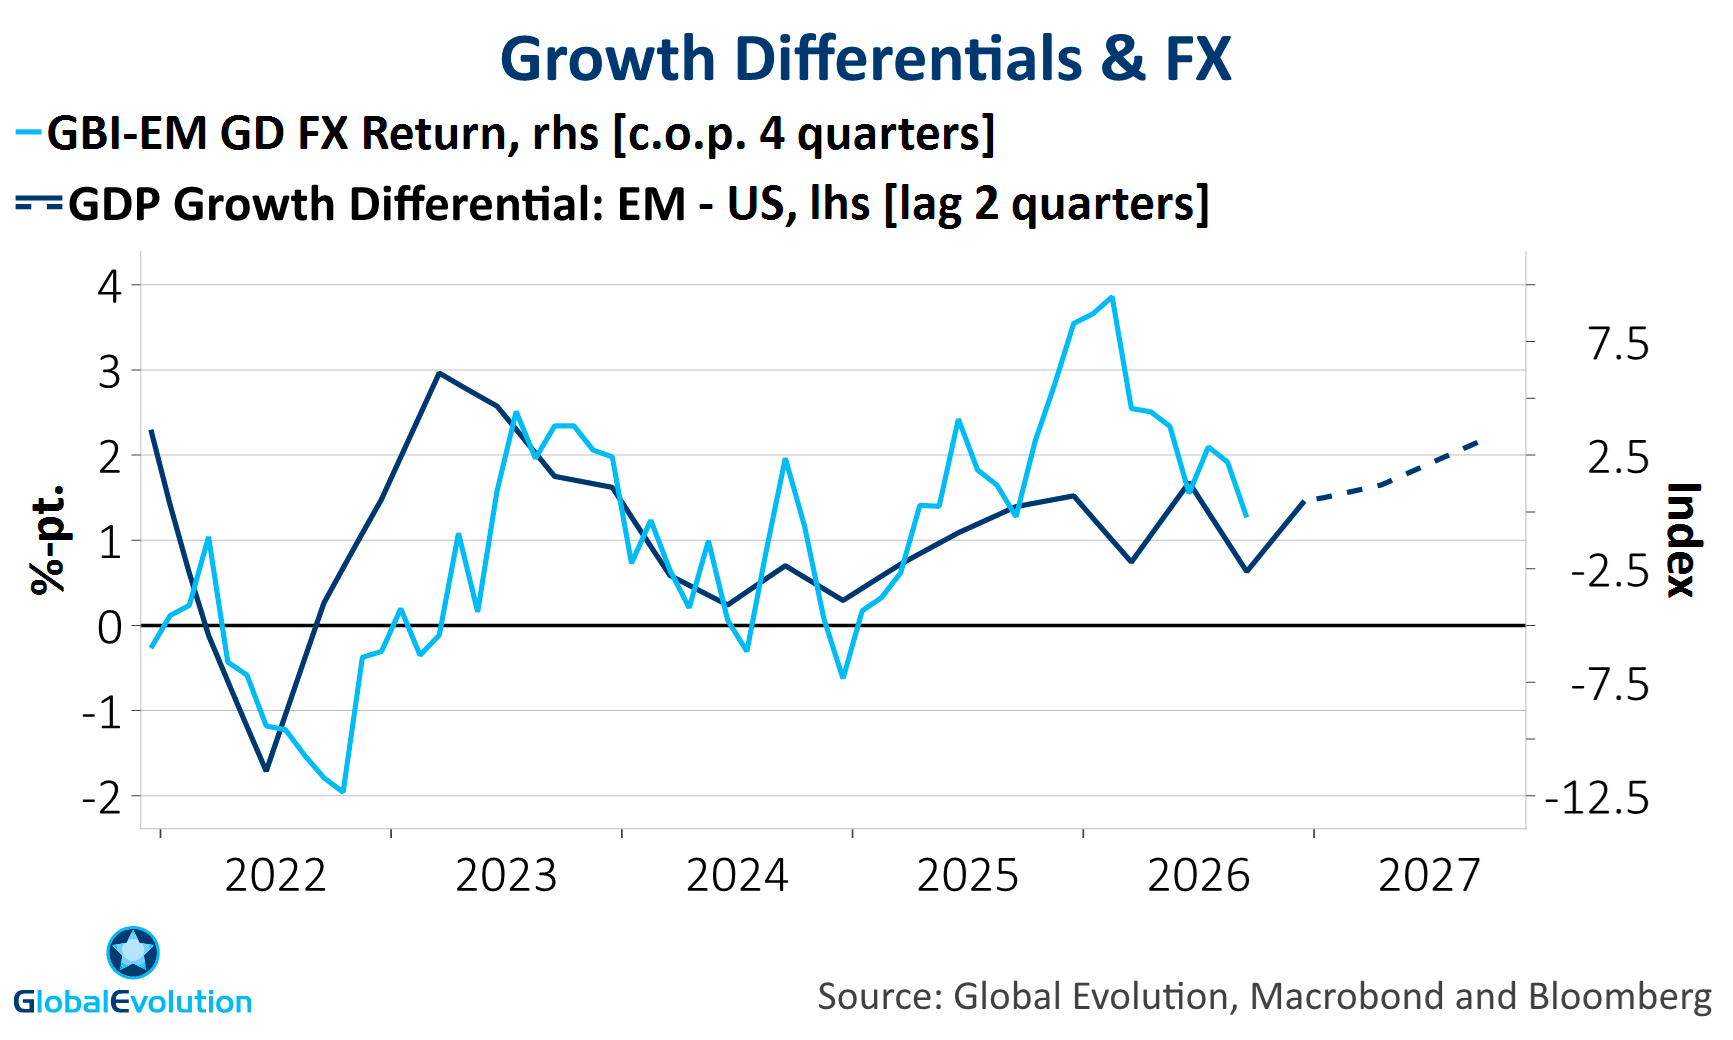
EM FX risk: Fundamental support
As we expected, local EMD outperformed despite a challenging environment for overall risk appetite. We believe there’s further upside based on a widening EM-US growth gap, USD positioning & valuation (EMFX fair).
Bottom-line
Carry & duration drive positive return expectations, but risk around spreads is biased to the upside.
Heavy DXY positioning, a widening EM-DM growth gap (first) and improving valuation (second) favours local EMD tactically.
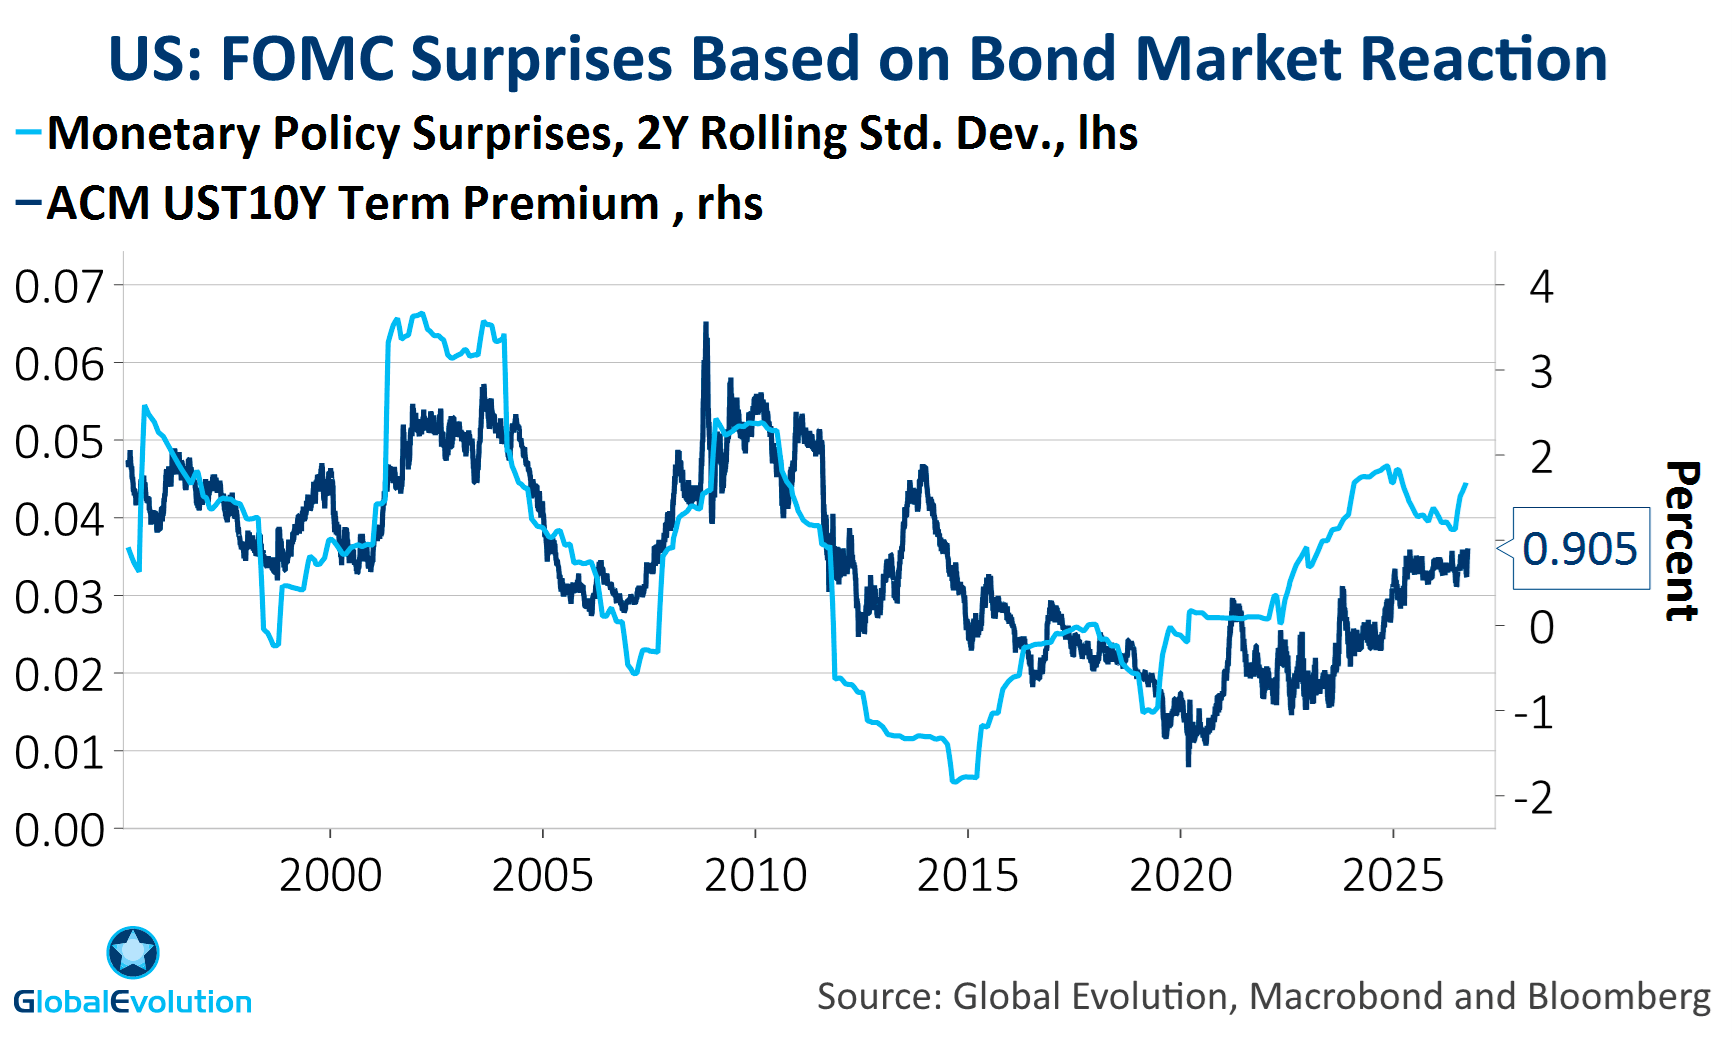
Higher term premium
Policy uncertainty & central bank surprise potential lifted the term premium. Together with the reversal of the savings glut, this points to a higher range for core yields.
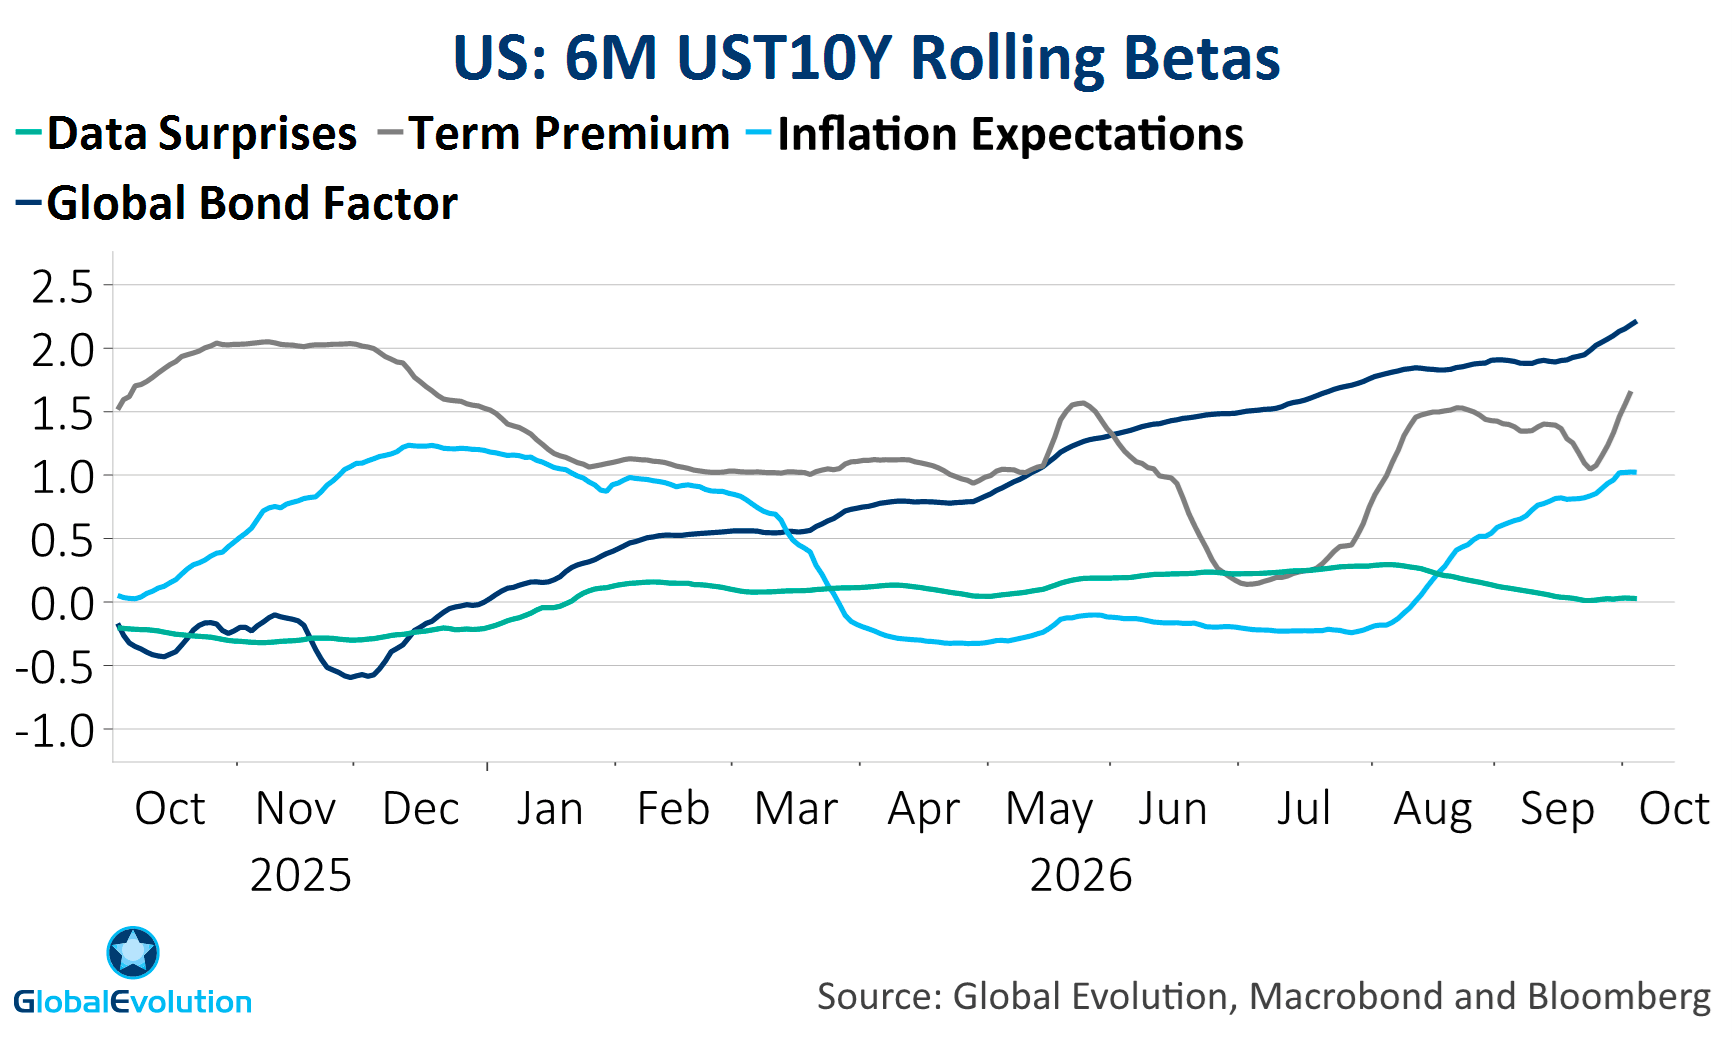
Duration decoupled
Duration decoupled from the growth backdrop as macro disappointments failed to contain yields. IN the coming months, we expect the upward pressure from inflation expectations to reverse and the term premium to stabilize (risk to the downside).
Falling UST rates support hard currency EMD over the strategic horizon
Peaking oil, dis-inflation, a fully-priced Fed & a clearer Fed reaction function creating downside risk to core yields next year → hard currency EMD to regain the upper hand in an asset allocation context.
Disclaimer & Important Disclosures
Global Evolution Asset Management A/S (“GEAM”) is incorporated in Denmark and authorized and regulated by the Danish FSA (Finanstilsynet). GEAM DK is located at Buen 11, 2nd Floor, Kolding 6000, Denmark.
GEAM has a United Kingdom branch (“Global Evolution Asset Management A/S (London Branch)”) located at Level 8, 24 Monument Street, London, EC3R 8AJ, United Kingdom. This branch is authorized and regulated by the Financial Conduct Authority under FCA # 954331. In Canada, while GEAM has no physical place of business, it has filed to claim the international dealer exemption and international adviser exemption in Alberta, British Columbia, Ontario, Quebec and Saskatchewan.
In the United States, investment advisory services are offered through Global Evolution USA, LLC (‘Global Evolution USA”), a Securities and Exchange Commission (“SEC”) registered investment advisor. Global Evolution USA is located at: 250 Park Avenue, 15th floor, New York, NY. Global Evolution USA is a wholly owned subsidiary of Global Evolution Financial ApS, the holding company of GEAM. Portfolio management and investment advisory services are provided to GE USA clients by GEAM. GEAM is exempt from SEC registration as a “participating affiliate” of Global Evolution USA as that term is used in relief granted by the staff of the SEC allowing U.S. registered investment advisers to use investment advisory resources of non-U.S. investment adviser affiliates subject to the regulatory supervision of the U.S. registered investment adviser. Registration with the SEC does not imply any level of skill or expertise. Prior to making any investment, an investor should read all disclosure and other documents associated with such investment including Global Evolution’s Form ADV which can be found at https://adviserinfo.sec.gov.
In Singapore, Global Evolution Fund Management Singapore Pte. Ltd (“Global Evolution Singapore”) has a Capital Markets Services license issued by the Monetary Authority of Singapore for fund management activities. It is located at Level 39, Marina Bay Financial Centre Tower 2, 10 Marina Boulevard, Singapore 018983.
GEAM, Global Evolution USA, and Global Evolution Singapore, together with their holding companies, Global Evolution Financial Aps and Global Evolution Holding Aps, make up the Global Evolution group affiliates (“Global Evolution”).
Global Evolution, Conning, Inc., Goodwin Capital Advisers, Inc., Conning Investment Products, Inc., a FINRA-registered broker-dealer, Conning Asset Management Limited, Conning Asia Pacific Limited, Octagon Credit Investors, LLC, and Pearlmark Real Estate, L.L.C. and its subsidiaries are all direct or indirect subsidiaries of Conning Holdings Limited (collectively, “Conning”) which is one of the family of companies whose controlling shareholder is Generali Investments Holding S.p.A. (“GIH”) a company headquartered in Italy. Assicurazioni Generali S.p.A. is the ultimate controlling parent of all GIH subsidiaries. Conning has investment centers in Asia, Europe and North America.
Conning, Inc., Conning Investment Products, Inc., Goodwin Capital Advisers, Inc., Octagon Credit Investors, LLC, PREP Investment Advisers, L.L.C. and Global Evolution USA, LLC are registered with the SEC under the Investment Advisers Act of 1940 and have noticed other jurisdictions they are conducting securities advisory business when required by law. In any other jurisdictions where they have not provided notice and are not exempt or excluded from those laws, they cannot transact business as an investment adviser and may not be able to respond to individual inquiries if the response could potentially lead to a transaction in securities.
Conning, Inc. is also registered with the National Futures Association. Conning Investment Products, Inc. is also registered with the Ontario Securities Commission. Conning Asset Management Limited is Authorised and regulated by the United Kingdom's Financial Conduct Authority (FCA#189316); Conning Asia Pacific Limited is regulated by Hong Kong’s Securities and Futures Commission for Types 1, 4 and 9 regulated activities; Global Evolution Asset Management A/S is regulated by Finanstilsynet (the Danish FSA) (FSA #8193); Global Evolution Asset Management A/S (London Branch) is regulated by the United Kingdom's Financial Conduct Authority (FCA# 954331); Global Evolution Asset Management A/S, Luxembourg branch, registered with the Luxembourg Company Register as the Luxembourg branch(es) of Global Evolution Asset Management A/S under the reference B287058. It is also registered with the CSSF under the license number S00009438.. Conning primarily provides asset management services for third-party assets.
This publication is for informational purposes and is not intended as an offer to purchase any security. Nothing contained in this communication constitutes or forms part of any offer to sell or buy an investment, or any solicitation of such an offer in any jurisdiction in which such offer or solicitation would be unlawful.
All investments entail risk, and you could lose all or a substantial amount of your investment. Past performance is not indicative of future results which may differ materially from past performance. The strategies presented herein invest in foreign securities which involve volatility and political, economic and currency risks and differences in accounting methods. These risks are greater for investments in emerging and frontier markets. Derivatives may involve certain costs and risks such as liquidity, interest rate, market, and credit.
This communication may contain Index data from J.P. Morgan or data derived from such Index data. Index data information has been obtained from sources believed to be reliable but J.P. Morgan does not warrant its completeness or accuracy. The Index is used with permission. The Index may not be copied, used, or distributed without J.P. Morgan's prior written approval. Copyright 2024, J.P. Morgan Chase & Co. All rights reserved.
This communication may contain aggregate peer analysis data has been obtained from eVestment Alliance LLC and its affiliated entities (collectively, "eVestment"). eVestment reserves all rights, including to ownership and distribution. eVestment collects information directly from investment management firms and other sources believed to be reliable; however, eVestment does not guarantee or warrant the accuracy, timeliness, or completeness of the information provided and is not responsible for any errors or omissions. Performance results may be provided with additional disclosures available on eVestment’s systems and other important considerations such as fees that may be applicable. Not for general distribution. * All categories not necessarily included; Totals may not equal 100%. Copyright 2013‐2024 eVestment Alliance, LLC. Returns less than a year are not annualized.
While reasonable care has been taken to ensure that the information herein is factually correct, Global Evolution makes no representation or guarantee as to its accuracy or completeness. The information herein is subject to change without notice. Certain information contained herein has been provided by third party sources which are believed to be reliable, but accuracy and completeness cannot be guaranteed. Global Evolution does not guarantee the accuracy of information obtained from third party/other sources.
The information herein is not intended to provide, and should not be relied upon for, accounting, legal or tax advice or investment recommendations.
Legal Disclaimer ©2026 Global Evolution.
This document is copyrighted with all rights reserved. No part of this document may be distributed, reproduced, transcribed, transmitted, stored in an electronic retrieval system, or translated into any language in any form by any means without the prior written permission of Global Evolution, as applicable.
Copyright © 2026 Global Evolution - All rights reserved